What Should You Do If You Cannot Pay Your Personal Loan EMI?
If you know that your upcoming EMI will be difficult to pay, take these steps:
1. Review Your Current Financial Position
Start by calculating:
- Monthly income
- Essential expenses
- Existing EMIs
- Credit card dues
- Other outstanding debts
- Available savings
- Amount currently overdue
This gives you a clearer picture of what you can realistically afford.
2. Check Your Loan Account
Review your latest loan statement and verify:
- Outstanding principal
- Interest payable
- Overdue amount
- Late-payment charges
- Number of missed EMIs
- Current loan status
Having accurate information is important before discussing repayment options.
3. Contact the Lender Through Appropriate Channels
If you are facing genuine financial difficulty, you can discuss your situation with the lender.
Depending on the circumstances and applicable lender policies, you may be able to explore repayment-related options.
4. Compare Your Available Options
Do not assume that settlement is automatically the answer.
Your situation may require consideration of:
- Revised repayment arrangements
- Loan restructuring
- Debt consolidation
- Continued repayment
- Loan settlement
The appropriate option depends on your ability to repay and the lender's policies.
What Happens If You Miss a Personal Loan EMI?
Missing an EMI can have several financial consequences.
Depending on the lender and loan agreement, you may face:
- Additional charges
- Accumulation of overdue amounts
- Continued interest or applicable charges
- Recovery communications
- Potential impact on your credit report
- Escalation of the account if repayment remains unresolved
The exact consequences depend on the loan agreement, lender policies and account status.
That is why it is better to address repayment difficulties early rather than simply ignoring the outstanding EMI.
Can I Ask My Lender for More Manageable Repayment Terms?
You can discuss your financial difficulty with the lender and ask whether any repayment options are available.
Depending on eligibility, the lender may have options involving changes to repayment terms.
However, approval is not automatic. The lender determines what options are available for a particular account.
Can Loan Restructuring Help When EMI Is Too High?
Loan restructuring may be considered when a borrower is having difficulty meeting the existing repayment terms.
A restructuring arrangement can involve changes to certain loan terms, subject to lender approval.
One possible outcome may be a more manageable monthly repayment, but borrowers should also consider the overall cost of the revised loan.
For example, extending the repayment period can potentially lower the monthly EMI while increasing the total interest payable over the longer period.
Can Debt Consolidation Help With Multiple EMIs?
If you have several loans or credit obligations, debt consolidation may be an option worth evaluating.
The basic idea is to combine multiple debts into a repayment structure, where eligible, so that managing several separate obligations may become simpler.
Before considering consolidation, compare:
- Interest rates
- Total outstanding balances
- New repayment period
- Processing or other applicable charges
- Total repayment cost
- Eligibility requirements
Debt consolidation is not suitable for every borrower.
What If I Have Already Missed Several EMIs?
If several payments have already been missed, first establish the current status of the loan account.
You should understand:
- Total overdue amount
- Current outstanding balance
- Charges applied
- Whether the account has been escalated
- Communications received from the lender
- Available repayment or resolution options
Depending on the account and lender's policies, restructuring, repayment arrangements or settlement may be considered.
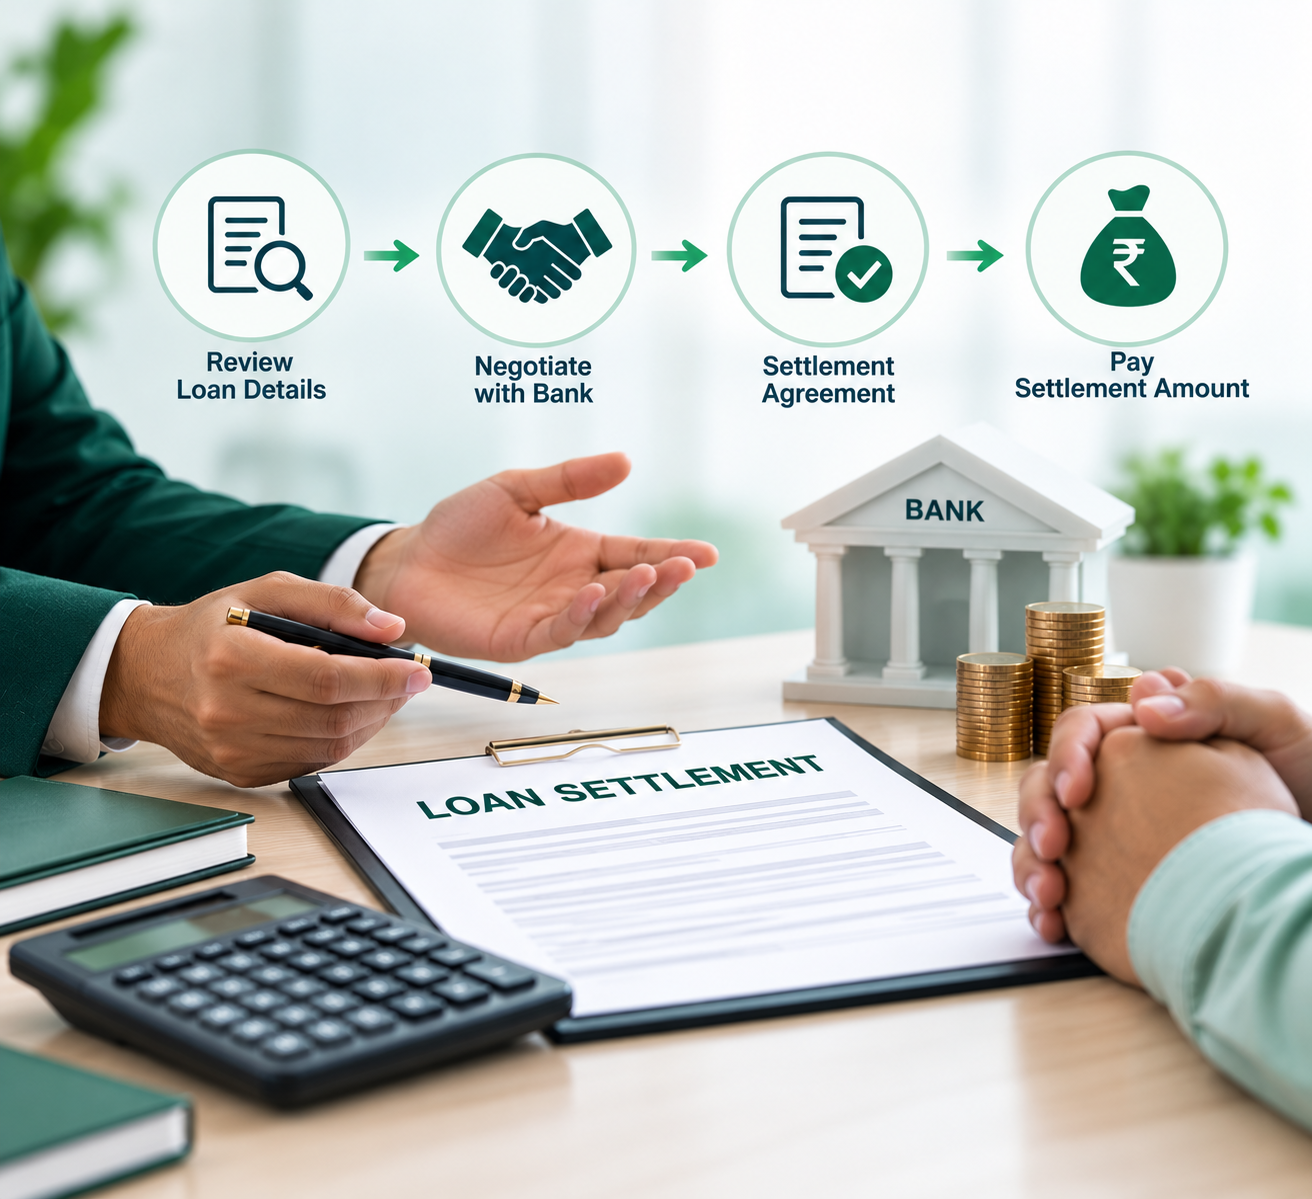
Can a Personal Loan Be Settled if I Cannot Repay It?
In some circumstances, a lender may agree to settle an outstanding personal loan under specific terms.
Settlement generally involves resolving the account for an amount agreed with the lender rather than continuing under the original repayment schedule.
However:
Settlement is not guaranteed.
The lender decides whether settlement is acceptable and what terms may apply.
Borrowers should also understand the potential impact of settlement on their credit profile before proceeding.
Does Loan Settlement Affect CIBIL?
It can.
A loan that is settled may be reported differently from a loan that has been fully repaid according to the original agreement.
The effect on your credit profile depends on factors such as:
- Account history
- Lender reporting
- Existing credit accounts
- Previous repayment behaviour
- Overall credit history
If you are considering settlement, understand the potential credit implications before accepting the arrangement.
What If Recovery Agents Are Contacting Me?
If your account has become overdue, you may receive recovery communications from the lender or its authorised representatives.
If you receive calls or messages:
- Verify who is contacting you.
- Ask for relevant account information.
- Keep records of communications.
- Avoid making payments through unverified channels.
- Communicate through appropriate lender channels.
- Seek professional guidance if you are unsure how to proceed.
Recovery activity does not mean you should stop reviewing your available repayment or resolution options.
What If I Receive a Legal Notice for an Unpaid Loan?
Do not ignore a legal notice.
First, verify the document and understand:
- Who issued it
- Which loan/account it concerns
- Amount being claimed
- Response deadline
- Documents referred to in the notice
If you do not understand the legal implications, consider obtaining appropriate legal advice.
A legal notice does not by itself establish that every amount stated is correct or that a particular legal outcome is certain. The circumstances and documents need to be reviewed.
Should I Stop Paying My Personal Loan EMI to Get a Settlement?
Borrowers should not assume that stopping payments will automatically result in a settlement.
Non-payment can lead to additional financial consequences and may affect your credit profile.
If you are struggling with repayment, it is better to understand your financial position and available options rather than intentionally missing payments based on the expectation of a particular settlement outcome.
Loan Restructuring vs Loan Settlement
|
Loan Restructuring |
Loan Settlement |
|
Modifies certain repayment terms |
Resolves outstanding dues under agreed settlement terms |
|
May make repayment more manageable |
May involve an agreed amount different from total outstanding dues |
|
Borrower generally continues repayment |
Borrower completes the agreed settlement payment |
|
Subject to lender approval |
Subject to lender approval |
|
Credit impact depends on the arrangement and reporting |
Can affect how the account is reported |
The appropriate option depends on your individual financial circumstances.
How to Decide Which Option May Be Appropriate
Ask yourself:
Can I still afford the EMI?
If yes, continuing repayment may be preferable to allowing the account to become overdue.
Has my financial situation temporarily changed?
If the difficulty is temporary, discussing repayment options with the lender may be useful.
Do I have several outstanding debts?
Debt consolidation or a broader debt-management approach may need to be evaluated.
Can I no longer realistically repay the loan under its current terms?
You may need to explore restructuring, settlement or other debt-resolution options.
Am I already dealing with overdue payments?
Review your account status and address the problem rather than allowing the arrears to continue without a plan.
Common Mistakes When Borrowers Cannot Pay EMI
Ignoring the lender
Not responding to repayment-related communication can make the situation harder to manage.
Taking another expensive loan without assessing affordability
Borrowing more money to pay an existing EMI can increase the overall debt burden.
Assuming settlement is guaranteed
Settlement depends on lender approval and individual circumstances.
Focusing only on the monthly payment
A lower EMI can sometimes mean a longer repayment period and higher total repayment cost.
Paying through unverified channels
Always verify payment instructions before transferring money.
Not keeping documents
Maintain statements, payment receipts, correspondence and any settlement documentation.
A Practical Checklist If You Cannot Pay Your EMI
Step 1: Calculate your total monthly debt obligations.
Step 2: Review your latest loan statement.
Step 3: Determine how much you can realistically afford.
Step 4: Identify whether your difficulty is temporary or long-term.
Step 5: Discuss available options through appropriate lender channels.
Step 6: Compare restructuring, consolidation, repayment and settlement where relevant.
Step 7: Understand potential credit-report consequences.
Step 8: Keep all financial and lender documentation.
Final Thoughts
Being unable to pay a personal loan EMI does not mean you should ignore the problem. The first step is to understand your financial position and the current status of your loan.
Depending on your circumstances, you may be able to explore repayment adjustments, restructuring, consolidation or settlement.
The right approach depends on factors such as your income, outstanding debt, repayment history, loan status and lender policies.
If your personal loan EMIs have become difficult to manage, a structured assessment of your debt situation can help you understand which options may be worth exploring.