


Small Personal Loan Defaults in India: What Happens If You Cannot Repay?
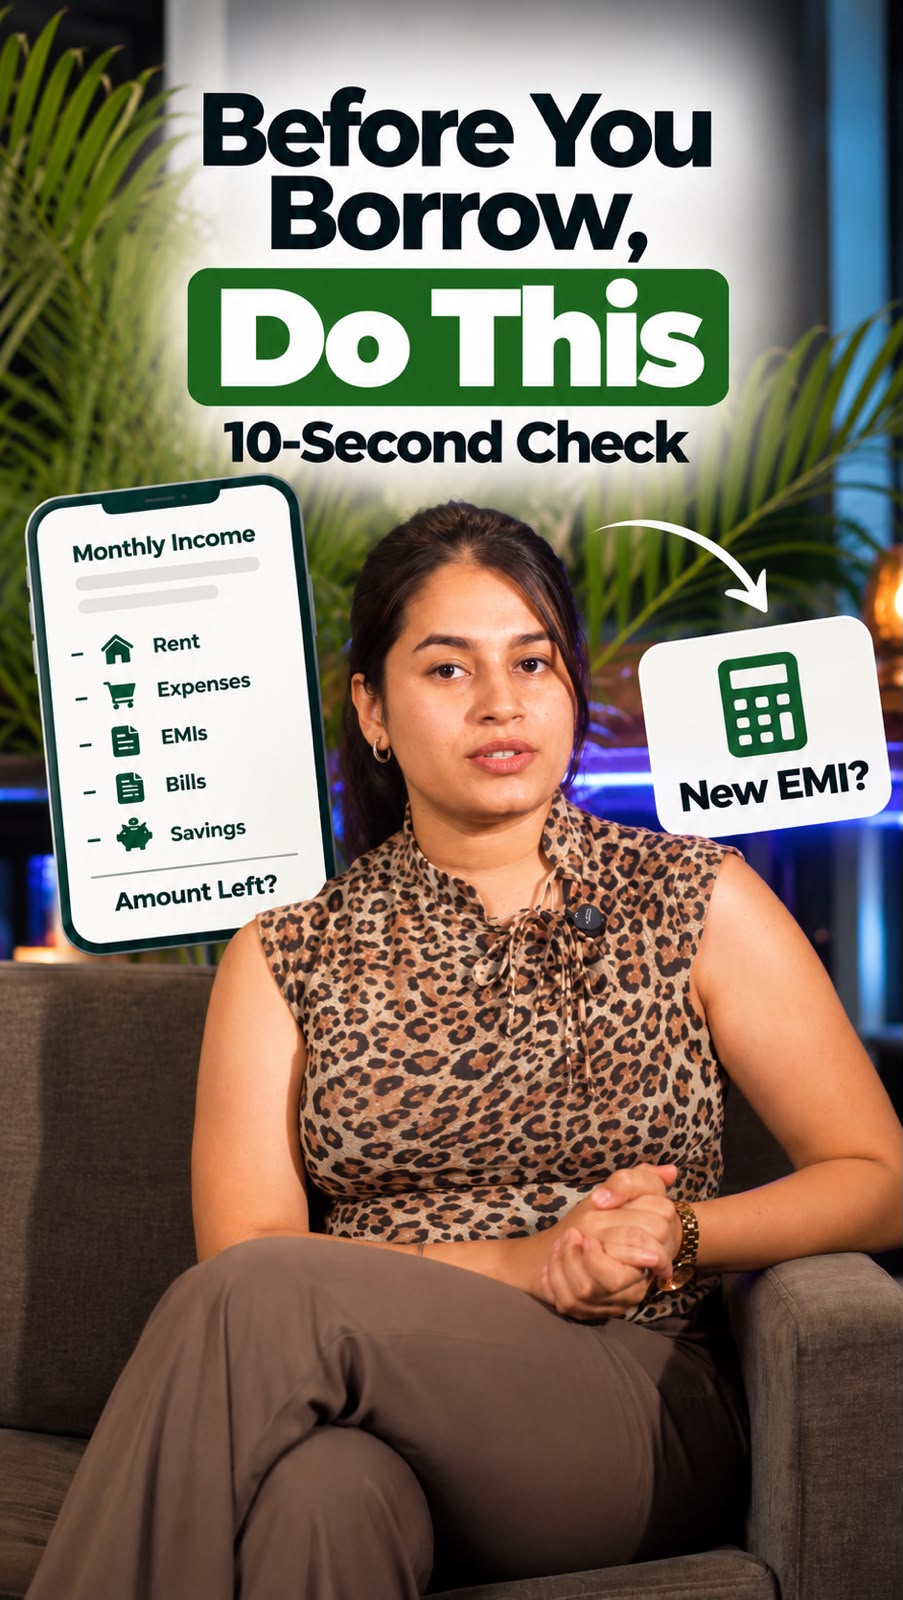
Small personal loans have become easier to access through banks, NBFCs and digital lending platforms. Borrowers can apply online, complete verification and receive funds without visiting a branch in many cases. These loans may help cover urgent expenses, medical bills, household requirements or temporary cash shortages. However, easy access to credit can also create repayment challenges when borrowers take multiple loans without properly assessing their monthly obligations. A small loan may look manageable initially. But when several EMIs, credit-card bills and household expenses fall due together, even a relatively small repayment can become difficult. The Reserve Bank of India's June 2026 Financial Stability Report highlighted rising delinquencies in fintech-originated small-ticket personal loans below ₹50,000. The report stated that fintech firms held a 56.8% share of this segment by March 2026, with delinquencies reported at 6.4%. CRIF's November 2026 How India Lends report also showed that personal loan delinquencies in the 91–180-day past-due category increased from 0.8% in June 2026 to 1.1% in September 2026. These figures relate to specific lending segments and reporting measures; they do not mean that every small personal loan borrower is facing default. However, they highlight why responsible borrowing and repayment planning matter.
Read More