What Is Personal Loan Restructuring?
Personal loan restructuring means modifying the existing repayment arrangement because the borrower is facing financial difficulty.
Instead of treating the original repayment schedule as unchanged, the lender may consider modifying certain terms of the loan.
Depending on the lender, loan product and borrower's circumstances, restructuring may involve changes such as:
- Extending the loan tenure
- Changing the EMI amount
- Altering the repayment schedule
- Providing a repayment concession where permitted
- Modifying the interest or other contractual terms
- Providing a temporary repayment arrangement
- Rescheduling certain payments
The exact restructuring options available are determined by the lender.
The fundamental objective is usually to make the repayment plan more manageable while allowing the borrower to continue servicing the debt.
RBI's prudential framework describes restructuring as a lender granting concessions because of financial difficulty, which can include changes to the payment period, payable amount, instalments or interest rate.
Simple example of restructuring
Suppose you have:
- Outstanding personal loan: ₹7,00,000
- Current EMI: ₹22,000
- Remaining tenure: 36 months
Your income falls because of a business slowdown or job change, and ₹22,000 per month is no longer affordable.
If the lender agrees to restructure the loan, the repayment period or other terms may be modified so that the monthly repayment becomes more manageable.
You may still have to repay the debt, but the repayment structure changes.
What Is Personal Loan Settlement?
Personal loan settlement is different.
In a settlement, the borrower and lender agree on an amount that will be accepted to resolve the outstanding claim, subject to the lender's approval and applicable terms.
For example, suppose a borrower has an outstanding liability of ₹8 lakh but is facing serious financial hardship and cannot realistically repay the entire amount under the original terms.
The borrower may approach the lender for a settlement.
If the lender agrees to a settlement amount of, for example, ₹5 lakh, the borrower would need to pay the agreed amount according to the settlement terms.
The actual amount, eligibility and conditions vary from case to case. There is no guaranteed settlement percentage or guaranteed reduction.
The Reserve Bank of India's framework defines a compromise settlement as a negotiated arrangement under which a regulated entity agrees to fully settle its claims in cash, potentially involving a sacrifice of part of the amount due.
Importantly, settlement is not the same as simply paying the loan in full.
A borrower should carefully review the lender's settlement documentation, including the amount to be paid, payment deadline, consequences of non-payment, account status and documentation to be provided after completion.
Personal Loan Settlement vs Restructuring: The Main Difference
The easiest way to understand the difference is this:
Restructuring changes how you repay the debt.
Settlement changes the amount and/or terms agreed to resolve the debt.
|
Factor |
Personal Loan Restructuring |
Personal Loan Settlement |
|
Main objective |
Make repayment more manageable |
Resolve an unaffordable outstanding liability through an agreed settlement |
|
Loan repayment |
Usually continues under revised terms |
Borrower pays the agreed settlement amount |
|
Outstanding principal |
Generally remains payable under revised terms |
May involve an agreed reduction or waiver, subject to lender approval |
|
EMI |
May be reduced or repayment schedule changed |
Usually replaced by settlement payment terms |
|
Tenure |
May be extended |
Depends on settlement agreement |
|
Financial hardship |
Can be suitable where future repayment is possible |
May be considered where full repayment is not realistically affordable |
|
Credit impact |
Depends on lender reporting and account history |
A settled status can have adverse credit implications |
|
Lender approval |
Required |
Required |
|
Guaranteed? |
No |
No |
|
Long-term objective |
Continue repayment |
Resolve the outstanding liability |
The important point is that neither option should be selected simply because the monthly payment or immediate amount looks lower.
The complete financial consequences need to be evaluated.
Why Do Borrowers Consider Restructuring?
Loan restructuring may become relevant when a borrower's financial situation has changed but there is still a reasonable possibility of repaying the loan.
Common situations include:
1. Temporary loss of income
A borrower may have lost employment or experienced a temporary reduction in income.
If income is expected to recover, changing the repayment schedule may be more appropriate than immediately considering settlement.
2. Business income has declined
Self-employed borrowers and small business owners may experience irregular cash flow.
The original EMI may have been affordable when the loan was taken but may no longer fit the current cash flow.
3. Unexpected financial expenses
Medical expenses, family emergencies, relocation, education costs or other major financial commitments can temporarily affect repayment capacity.
4. EMI has become too high compared with current income
Even if the borrower has not completely stopped paying, the EMI may be consuming too much of the available monthly income.
5. Multiple financial obligations
A borrower may have several loans, credit cards and other monthly commitments.
In such cases, the borrower needs to assess the entire debt position rather than looking at one EMI in isolation.
Why Do Borrowers Consider Loan Settlement?
Settlement generally becomes relevant when the borrower is facing more severe financial difficulty and cannot realistically repay the full outstanding amount according to the original arrangement.
Potential situations may include:
- Long-term loss of income
- Significant reduction in household income
- Multiple unpaid loans
- Persistent EMI defaults
- Growing outstanding dues
- High debt compared with available income
- Recovery pressure
- Legal notices or advanced recovery stages
- Lack of realistic capacity to continue the original repayment schedule
However, financial difficulty alone does not automatically mean a lender will approve settlement.
The lender ultimately decides whether a settlement proposal is acceptable.
RBI's compromise-settlement framework requires regulated entities to have board-approved policies governing such settlements.
Personal Loan Restructuring: How Does It Work?
The restructuring process can vary by lender, but the broad process may look like this.
Step 1: Assess your financial situation
Before approaching the lender, understand:
- Monthly income
- Essential household expenses
- Existing EMIs
- Credit card dues
- Other debts
- Current outstanding personal loan
- Missed payments, if any
- Available savings
- Expected future income
This gives you a realistic picture of what you can actually afford.
Step 2: Approach the lender
Explain the reason for financial difficulty and provide the information requested by the lender.
The lender may ask for documents supporting your financial situation.
Step 3: Lender evaluates repayment capacity
The lender may assess whether the revised arrangement is financially viable.
Restructuring is not simply an automatic right available whenever a borrower requests a lower EMI.
The lender evaluates the proposal according to its applicable policies and regulatory requirements.
Step 4: Revised terms are proposed
If the lender agrees, the borrower may receive revised repayment terms.
These could potentially include a different tenure, EMI or repayment schedule, depending on the arrangement.
Step 5: Documentation and implementation
The revised terms should be documented properly.
Do not rely solely on a verbal promise from a caller or recovery representative.
Always ask for the revised terms in writing and understand the complete repayment obligation.
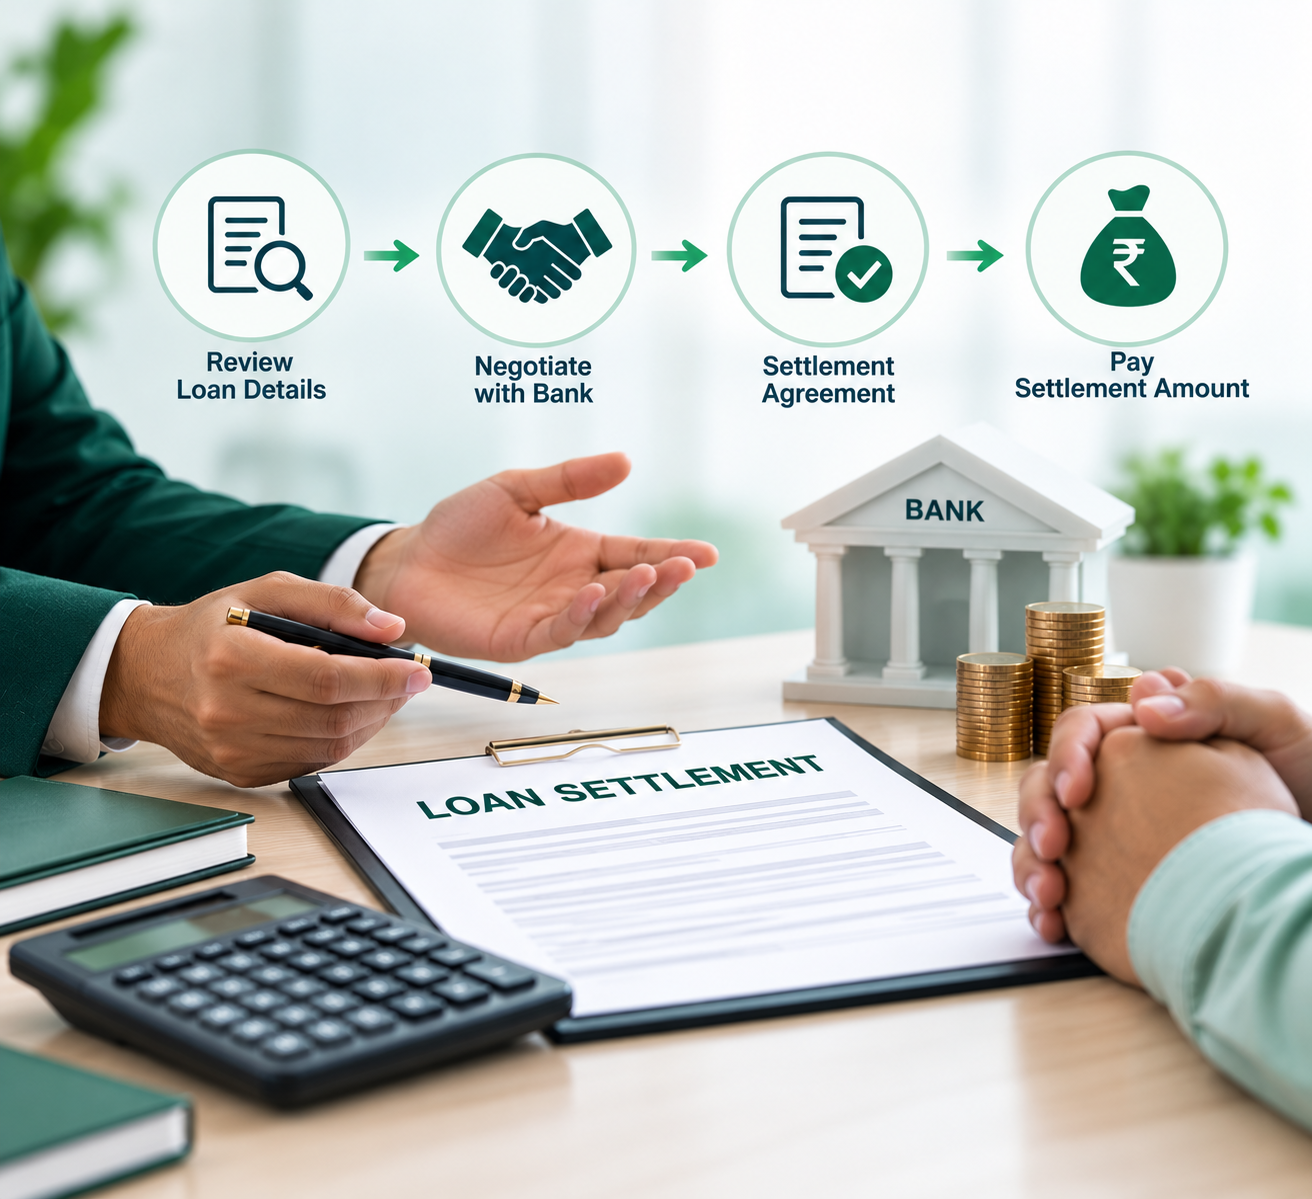
Personal Loan Settlement: How Does It Work?
Settlement also involves multiple stages.
Step 1: Understand the outstanding amount
First, determine the actual amount being claimed by the lender.
Review:
- Principal outstanding
- Interest
- Applicable charges
- Overdue amounts
- Other contractual dues
- Recovery-related communications
- Legal notices, if applicable
Step 2: Assess your actual repayment capacity
A settlement discussion should be based on a realistic assessment of what you can arrange.
Do not promise an amount that you cannot pay.
Step 3: Settlement proposal
A settlement proposal may be discussed with the lender.
The lender may accept, reject or modify the proposal.
Step 4: Obtain written confirmation
If settlement is approved, obtain formal written documentation from the lender.
The document should clearly identify the agreed amount and applicable terms.
Step 5: Make payment according to the agreed terms
Payment should be made only through the lender's official and authorised payment channels.
ReducedDebts itself also warns customers to pay only through official links and not to personal UPI, QR or bank accounts.
Step 6: Obtain relevant closure/settlement documentation
After fulfilling the settlement terms, keep all payment receipts and lender documentation safely.
Do not assume that making one payment automatically means the account has been updated everywhere.
Which Is Better: Settlement or Restructuring?
For many borrowers, the better option depends primarily on one question:
Can you realistically repay the debt if the repayment terms are modified?
If the answer is yes, restructuring may deserve consideration.
If the answer is no, and the borrower genuinely cannot repay the full amount despite a revised repayment arrangement, settlement may need to be evaluated.
This distinction is important.
Restructuring is generally more repayment-oriented.
You are saying:
"I cannot manage the current repayment structure, but I may be able to repay if the terms are modified."
Settlement is generally resolution-oriented.
You are saying:
"I cannot realistically repay the full outstanding amount under the existing or revised structure, so I want to explore whether the lender will accept an agreed settlement."
Neither statement automatically guarantees approval.
Is Restructuring Better for Your CIBIL Score?
Borrowers often assume that restructuring will have no impact on their credit profile.
That is not a safe assumption.
Credit reporting depends on how the lender reports the account and the borrower's repayment history.
A restructuring arrangement can therefore have credit-report implications, particularly if the account already has overdue payments or other negative repayment history.
TransUnion CIBIL reports credit behaviour and repayment-related information to lenders through credit information reports, which are used as part of credit-risk assessment.
Therefore, before agreeing to restructuring, ask the lender:
- How will the account be reported?
- Will overdue amounts remain visible?
- What happens to the repayment history?
- Will the revised arrangement be reflected in the credit report?
- What happens if you miss a payment under the revised terms?
Do not make a decision based solely on the promise of a lower EMI.
Does Personal Loan Settlement Affect CIBIL?
Settlement can have a more significant credit-profile consequence.
When a lender accepts less than the full contractual dues to resolve the account, the account may be reported differently from a loan that has been fully repaid according to its terms.
A borrower should therefore understand the difference between:
Closed account
and
Settled account
These are not necessarily viewed in the same way by future lenders.
A settled account may indicate that the lender accepted an agreed settlement rather than receiving the full contractual amount.
This can affect how future lenders assess the borrower's creditworthiness.
The exact effect depends on the individual's complete credit history, lender reporting and future repayment behaviour.
Settlement vs Restructuring: Which Has the Bigger Credit Impact?
There is no universal score change that can be promised.
A borrower's credit profile depends on multiple factors, including:
- Existing repayment history
- Number of overdue accounts
- Days past due
- Credit utilisation
- Number of active loans
- Recent credit enquiries
- Account status
- Payment behaviour after the resolution
- Information reported by lenders
TransUnion CIBIL's current credit-risk products incorporate detailed repayment patterns and historical credit behaviour when assessing borrowers.
Therefore, it is incorrect to say:
"Settlement will reduce your CIBIL score by exactly X points."
The actual impact varies.
Can Restructuring Reduce Your Total Loan Amount?
Usually, borrowers should not assume that restructuring means their principal automatically disappears.
The primary purpose of restructuring is generally to modify the repayment arrangement.
For example, a lender may modify:
- Tenure
- EMI
- Repayment schedule
- Certain contractual terms
The borrower may still be required to repay the underlying debt according to the revised arrangement.
This is why restructuring and settlement should not be treated as interchangeable terms.
Can Settlement Reduce the Amount You Have to Pay?
A settlement may involve the lender agreeing to accept an amount lower than the total contractual claim.
However, the amount is not predetermined.
There is no universal rule such as:
"Personal loans can always be settled at 40%."
or
"Every borrower can settle at 50%."
Such statements can be misleading.
The outcome can depend on:
- Lender policy
- Age of the account
- Outstanding amount
- Repayment history
- Financial hardship
- Recovery stage
- Borrower's financial position
- Availability of funds
- Documentation
- Negotiation
- Lender's assessment
RBI's 2023 framework specifically provides for board-approved policies governing compromise settlements and the permissible sacrifice by regulated entities.
What If You Can Still Afford Some EMI?
This is where borrowers often make the wrong decision.
If you can still afford a reasonable repayment amount, you should not automatically assume that settlement is the best option.
For example:
Situation A
Monthly income: ₹80,000
Essential expenses: ₹45,000
Existing EMI: ₹25,000
There may still be some repayment capacity.
Depending on the circumstances, restructuring or another repayment solution may be worth exploring before settlement.
Situation B
Monthly income: ₹35,000
Essential expenses: ₹30,000
Multiple EMIs: ₹25,000
Here, the borrower has a structural affordability problem.
Simply extending the loan may not solve the underlying issue.
A broader debt assessment may be required.
What If You Have Already Missed Several EMIs?
Missing EMIs changes the situation.
Once payments become overdue, you may face:
- Additional financial charges according to the loan terms
- Recovery communication
- Credit-report consequences
- Increased financial pressure
- Potential legal communication
- Difficulty obtaining fresh credit
The exact consequences depend on the lender, loan agreement, account status and applicable rules.
At this stage, ignoring the lender usually does not solve the problem.
Instead, the borrower should understand the account status and evaluate the available options.
Can You Restructure After Default?
Possibly, but there is no blanket guarantee.
The availability of restructuring depends on the lender's policies, the borrower's circumstances, account status and applicable regulatory framework.
The RBI's stressed-assets framework recognises restructuring as a resolution mechanism, but lenders are required to follow applicable prudential requirements and their own approved policies.
Therefore, a borrower should not assume:
"I missed my EMI, so the bank must restructure my loan."
That is not how restructuring works.
Can You Settle a Personal Loan Before Default?
A settlement is not necessarily the same thing as a normal prepayment or foreclosure.
If you are financially capable of repaying the full loan, it is important to compare:
- Normal repayment
- Foreclosure/prepayment
- Restructuring
- Consolidation
- Settlement
before making a decision.
Settlement is generally relevant to situations involving financial distress rather than simply a desire to close a loan early.
Personal Loan Settlement vs Foreclosure
These terms are often confused.
Foreclosure
You repay the applicable outstanding amount required to close the loan, subject to the lender's terms and applicable charges.
Settlement
The lender agrees to accept a negotiated amount to resolve the liability.
Therefore:
Foreclosure = repayment-based closure
Settlement = negotiated resolution
A borrower should carefully check the lender's documentation to understand the account status after payment.