What Is Loan Settlement?
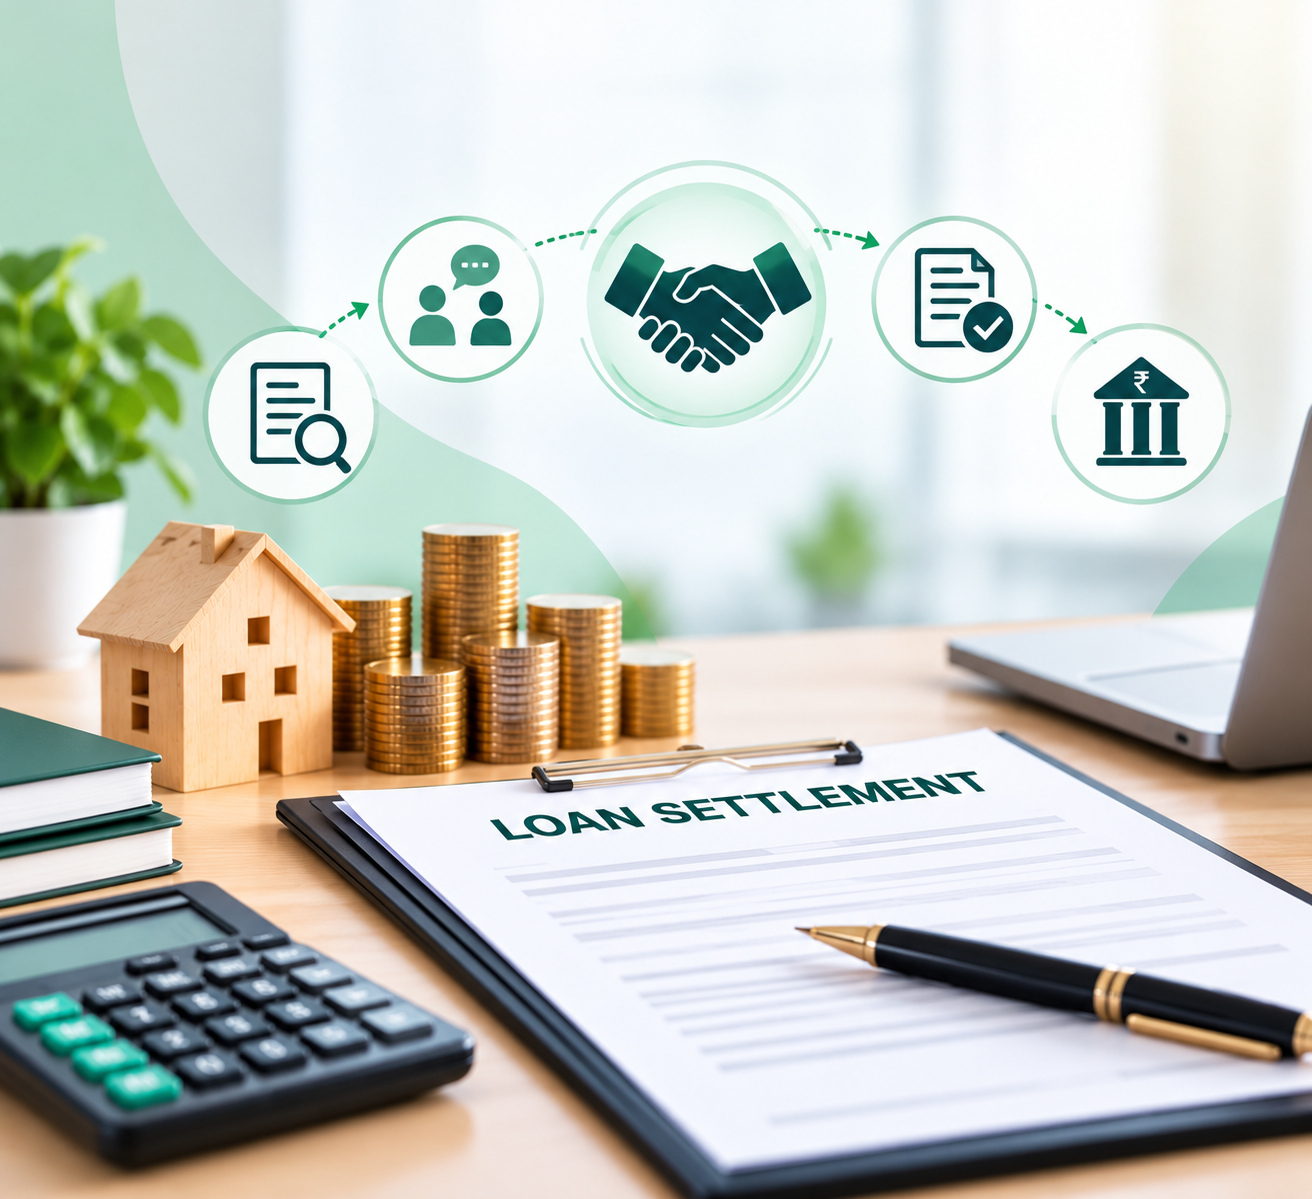
Loan settlement is an arrangement under which a lender agrees to resolve an outstanding loan account for an amount and terms agreed between the lender and borrower.
It is different from simply paying a loan according to the original repayment schedule.
A settlement may be considered when a borrower is experiencing significant financial difficulty and continuing with the original repayment terms is no longer realistically manageable.
Loan Settlement Process: Step by Step
Step 1: Assess Your Financial Situation
Before considering settlement, first understand your overall financial position.
Review:
- Monthly income
- Essential household expenses
- Existing EMIs
- Total outstanding debt
- Missed or overdue payments
- Credit card obligations
- Other financial commitments
This assessment helps determine whether settlement is appropriate or whether another solution may be more suitable.
Step 2: Understand Your Outstanding Loan Amount
Obtain the latest available information about the loan from your lender.
Check:
- Principal outstanding
- Interest due
- Overdue instalments
- Late-payment charges
- Other applicable charges
- Current account status
Do not rely only on an old statement or an amount communicated informally.
Step 3: Review Your Available Debt Solutions
Loan settlement is only one possible approach.
Depending on your circumstances, you may need to evaluate options such as:
- Loan restructuring
- Revised repayment arrangements
- Debt consolidation
- Continued repayment
- Loan settlement
The appropriate option depends on your financial circumstances, lender policies and ability to repay.
Step 4: Discuss the Situation With the Lender
If settlement is being considered, the borrower or authorised representative can discuss the account with the lender through appropriate channels.
The discussion may involve:
- Current outstanding balance
- Financial difficulty
- Proposed repayment capability
- Possible resolution options
- Settlement terms, if offered
A lender is not required to accept every settlement proposal.
Step 5: Review the Settlement Offer
If the lender agrees to consider settlement, carefully review the proposed terms.
Pay attention to:
Settlement amount:
How much needs to be paid?
Payment deadline:
When must the amount be paid?
Payment method:
Where and how should payment be made?
Account status:
How will the account be reported?
Documentation:
What confirmation will the lender provide after payment?
Never make a settlement payment based solely on a verbal promise when written confirmation is available.
Step 6: Make the Agreed Payment
Once the settlement terms have been properly documented and accepted, make the payment according to the agreed arrangement.
Use verified payment channels and retain:
- Payment receipt
- Transaction reference
- Bank statement
- Settlement communication
- Any related correspondence
These records can become important later if you need to verify the settlement.
Step 7: Obtain Settlement Documentation
After completing the agreed payment, request the relevant account documentation from the lender.
Depending on the lender and circumstances, this may include:
- Settlement letter
- Payment confirmation
- Updated account statement
- Relevant closure or settlement documentation
Keep these records safely.
Step 8: Check Your Credit Report
After the lender has processed the settlement, review your credit report to ensure the account information is accurately reflected.
Remember that a settled account is not necessarily reported in the same way as an account that was fully repaid and closed according to the original loan terms.
How Long Does Loan Settlement Take?
There is no single timeline that applies to every loan settlement.
The duration can depend on:
- Lender's internal process
- Account status
- Outstanding amount
- Documentation required
- Negotiation
- Borrower's ability to make the agreed payment
- Lender approval
Therefore, borrowers should rely on the specific timeline communicated by the lender rather than assuming that every settlement follows the same schedule.
Can a Defaulted Loan Be Settled?
A loan that has become overdue or defaulted may still be considered for settlement, depending on the lender's policies and the individual account.
However, default does not automatically qualify someone for settlement.
The lender may consider the account history, outstanding dues and the borrower's circumstances before deciding whether to offer settlement terms.
Can Multiple Loans Be Settled?
If you have several outstanding loans, each account may need to be evaluated separately.
Different lenders can have different:
- Settlement policies
- Documentation requirements
- Approval processes
- Payment conditions
- Reporting practices
A borrower with multiple debts should therefore review the complete debt position rather than focusing on only one account.
Does Loan Settlement Affect CIBIL?
It can.
When an account is settled rather than repaid in full according to the original loan agreement, the account can be reported differently to credit bureaus.
The effect on your credit profile depends on your broader credit history and how the lender reports the account.
Before accepting settlement, borrowers should understand this potential consequence and consider their future borrowing needs.
Is Loan Settlement the Same as Loan Closure?
No.
Loan Closure
Generally refers to repayment of the amount due under the original loan terms, after which the account is closed.
Loan Settlement
Refers to an arrangement where the lender agrees to resolve outstanding dues under specific settlement terms.
Because the two outcomes can be reported differently, borrowers should understand the distinction before choosing an option.
Can Loan Settlement Reduce the Amount You Need to Pay?
A lender may agree to accept a settlement amount that is different from the total outstanding dues.
However, there is no universal settlement percentage.
The final terms can depend on the lender, account status and borrower's circumstances.
Be cautious of anyone promising a fixed or guaranteed reduction without considering the individual loan account.
What Documents Should You Keep During Loan Settlement?
Maintain a complete file containing:
- Loan agreement
- Latest account statement
- Outstanding balance information
- Settlement proposal
- Settlement letter
- Payment receipts
- Bank transaction records
- Email or written correspondence
- Final account documentation
Keeping these records helps you maintain a clear history of the resolution process.
What Should You Avoid During Loan Settlement?
Don't rely only on verbal commitments
Important settlement terms should be properly documented.
Don't ignore the lender's original account information
Verify the outstanding amount before discussing settlement.
Don't make payments to unverified accounts
Use appropriate, verified payment channels.
Don't assume settlement automatically improves your credit score
Settlement can have credit-report implications.
Don't assume settlement is the only solution
Compare it with restructuring, consolidation and other repayment options where relevant.
Loan Settlement vs Restructuring
|
Loan Settlement |
Loan Restructuring |
|
Resolves outstanding dues under agreed settlement terms |
Modifies certain repayment terms |
|
May involve an amount different from total outstanding dues |
Generally continues the loan under revised terms |
|
Can have credit-report implications |
Credit impact depends on the restructuring arrangement |
|
Subject to lender approval |
Subject to lender eligibility and approval |
|
May be considered when repayment is severely difficult |
May be considered when repayment is possible under revised terms |
Neither option is automatically suitable for every borrower.
What Should You Do Before Starting Loan Settlement?
A practical checklist is:
1. Calculate your total outstanding debt.
Know exactly what you owe.
2. Review your monthly repayment capacity.
Understand what you can realistically afford.
3. Check your loan statements.
Verify the account information.
4. Understand your alternatives.
Consider restructuring, consolidation and other available options.
5. Verify settlement terms.
Do not make assumptions about the final amount or conditions.
6. Keep everything documented.
Save payment records and lender communications.
7. Understand the credit implications.
Know how settlement may affect your credit profile.
Final Takeaway
The loan settlement process in India generally involves financial assessment, review of outstanding dues, discussion of available options, lender approval, documented settlement terms, payment and post-settlement documentation.
Settlement can be relevant in some difficult financial situations, but it should not be approached as a guaranteed way to reduce debt. Every loan account is different, and the lender ultimately determines whether settlement can be offered and on what terms.
If you are struggling with your loan EMIs or multiple outstanding loans, assessing your complete financial situation first can help you understand which debt-resolution options may be relevant.