We help individuals break free from credit card and loan debts through direct bank negotiation and legal guidance, saving up to 50% on settlements.
Shield yourself from unlawful harassment and legal notices.
Substantially lower your principal debt and eliminate late fees.
Managing debt can feel overwhelming, especially when multiple payments, high interest rates, and financial responsibilities start to add up.
Understanding your options can help you make confident and informed financial decisions.
Take the first step toward finding a solution that fits your financial situation.By exploring your available options and understanding how each approach works, you can create a clearer path toward managing your debt and working toward greater financial stability.
Get a clearer picture of your outstanding balances, monthly payments, interest rates, and the challenges affecting your finances.
Learn about potential debt relief solutions and understand which options may help you work toward becoming financially stable.
Having the right information can make it easier to understand your choices and take the next step toward a healthier financial future.
Smart financial habits can help you maintain and gradually improve your credit profile
Set up auto-pay for credit cards and loans to avoid late payment penalties and score drops.
Keep your credit utilization ratio below 30% of your total assigned credit limit.
Regularly audit your CIBIL report for errors or unauthorized inquiries and dispute them.
Maintain a healthy balance between secured (home/auto) and unsecured (credit card) loans.
Debt can quickly become overwhelming. If any of these situations sound familiar, we're here to help you find a practical way forward.
Monthly payments are becoming difficult to manage.
Debt is affecting your peace of mind and daily life.
Frequent collection calls are adding more pressure.
Managing several card balances has become difficult.
Your outstanding balance keeps growing every month.
You have received a notice regarding unpaid dues.
Interest and penalties are making repayment harder.
Your income isn't enough to cover all your repayments.
Share your details and talk to our experts.
We review your documents and analyze your case.
Our experts negotiate with the bank on your behalf.
Pay the agreed amount and become debt free.
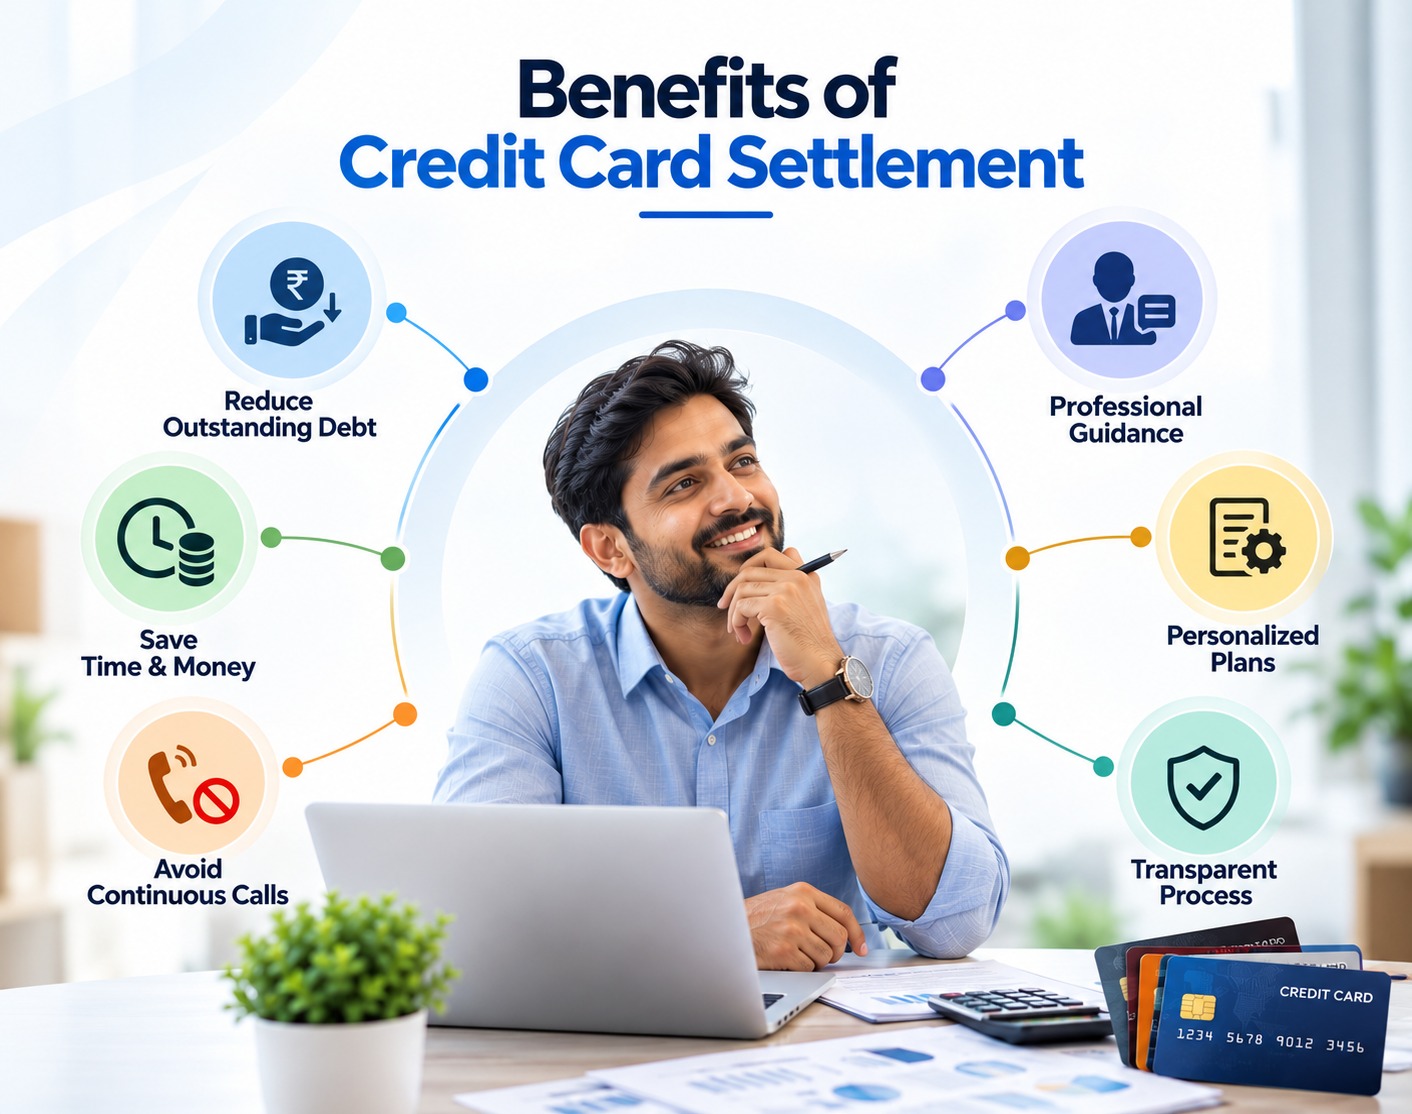
Settle your debt for a lower amount than you owe.
Save on high interest, late fees and finance charges.
Put an end to stressful collection calls and legal notices.
Expert support at every step of the settlement process.
Get settlement solutions tailored to your financial situation.
No hidden charges. 100% transparent and ethical.
We empower individuals to escape high-interest debt cycles with legally sound and financially practical resolution strategies.
Your personal data and financial profile are secured with bank-grade encryption and legal privacy protocols.
Our experienced legal panel stops illegal recovery tactics, direct calls, and legal notices.
Get a personal financial advisor who directly negotiates with banks to maximize your debt savings.
Direct payments to banks with zero hidden charges and guaranteed formal closure certificate (NOC).
Calculate how much you can save and become debt free sooner.
See how we helped our clients become debt-free with huge savings on their settlements.
""I was struggling with high interest on 3 credit cards. Reduced Debts team negotiated with banks and settled my ?4.5 Lakh debt for just ?2.0 Lakh.""

""Recovery agent calls were stressing me every day. Their legal team handled everything professionally and closed my settlement safely.""

Credit card settlement may be worth evaluating when your outstanding balance has become difficult to repay and continuing minimum payments is no longer financially sustainable. Your income, outstanding balance, repayment history, and overall debt situation should be reviewed before deciding whether settlement is appropriate.
Possibly. Paying only the minimum amount can leave a significant balance outstanding because interest and other applicable charges may continue to accumulate. If you are struggling to clear the balance, a proper assessment can help determine whether settlement or another repayment solution is more suitable.
A credit card account with overdue payments may still be considered for settlement, depending on the account status and the card issuer's policies. The longer an account remains unpaid, the more important it becomes to understand the outstanding amount, recovery stage, and consequences before negotiating.
There is no standard settlement percentage that applies to every credit card account. The final amount depends on factors such as the outstanding balance, account status, repayment history, financial circumstances, and the settlement terms accepted by the card issuer.
Yes, it can. If the card issuer reports the account as “settled” rather than “closed,” it can negatively affect your credit profile. The impact depends on your broader credit history and how the account is reported, so the consequences should be understood before proceeding.
After the agreed settlement amount is paid, the card account is handled according to the issuer's settlement and reporting process. You should obtain written confirmation of the settlement and retain all payment receipts and account-related documents for your records.
Multiple credit card accounts can be assessed together, but each account may have a different issuer, outstanding balance, account status, and settlement requirement. A combined assessment can help you understand the position of each card and prioritize your debt-resolution strategy
Keep records of calls, messages, emails, and other communications related to the account. Avoid making payment or settlement decisions solely under pressure. If you are facing inappropriate recovery practices, professional guidance can help you understand the appropriate communication and complaint process.
Can I settle credit card debt if I have received a legal notice?
Before making the payment, verify the written settlement terms, agreed settlement amount, payment deadline, card/account details, and payment instructions. After payment, retain the settlement confirmation, receipts, and any documentation issued by the card issuer regarding the account status.