What Is Loan Settlement?
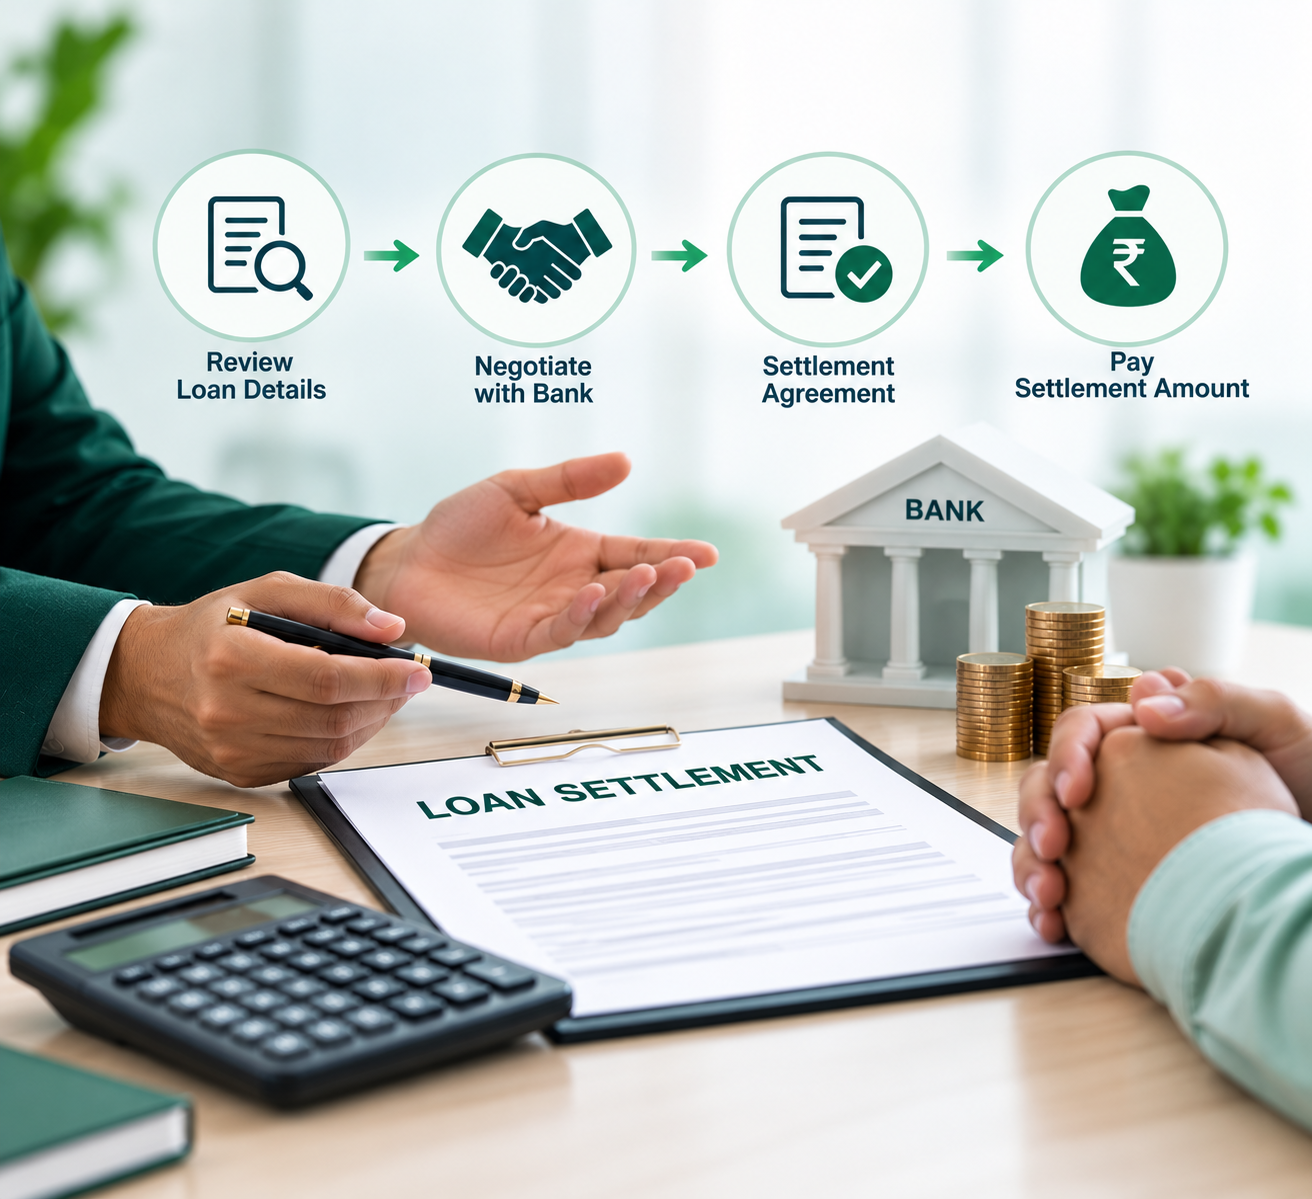
Loan settlement is an arrangement between a borrower and lender to resolve outstanding loan dues under specific terms agreed by the lender.
It may be considered when a borrower is experiencing substantial financial difficulty and cannot realistically continue repaying the loan according to the original repayment schedule.
For example, a borrower may have:
- Lost a source of income
- Experienced a significant financial setback
- Accumulated several loans
- Fallen behind on EMI payments
- Struggled with increasing debt obligations
- Become unable to maintain the original repayment schedule
If a lender agrees to settlement, the borrower may be required to pay an agreed settlement amount within specified terms.
The exact settlement amount, conditions and approval process depend on the lender and individual account.
There is no universal settlement amount or guaranteed percentage of debt reduction.
Why Does Loan Settlement Affect Your CIBIL Score?
Credit bureaus maintain information about your borrowing and repayment behaviour.
When a loan is fully repaid according to the original agreement, the lender may report the account as closed.
A settlement is different.
If the lender agrees to accept a settlement amount rather than the full contractual dues, the account may be reported with a settled status.
This distinction matters because lenders reviewing your credit history may consider the account history when assessing future credit applications.
Therefore, the impact of loan settlement is not simply about a number such as your CIBIL score. It can also involve how the account is represented in your overall credit history.
Settled vs Closed Loan: What Is the Difference?
This is one of the most important concepts borrowers should understand.
Closed Loan
A loan is generally considered closed when the borrower has fulfilled the repayment obligations under the original loan agreement and the lender closes the account.
For example:
You borrowed a personal loan, made the required repayments and ultimately paid the amount due under the agreed terms.
The account may then be reported as closed.
Settled Loan
A settled loan involves an agreement between the borrower and lender to resolve outstanding dues under settlement terms.
The borrower may pay an agreed amount, after which the lender updates the account according to the applicable reporting process.
The account can therefore have a different status from a normally closed loan.
Why does this distinction matter?
When a future lender reviews your credit history, the difference between a normally closed account and a settled account may be relevant to its assessment.
This is why borrowers should understand the potential credit consequences before choosing settlement.
Does Loan Settlement Reduce Your CIBIL Score?
It is possible for loan settlement to negatively affect your credit profile.
However, there is no single fixed number of points that applies to every borrower.
The effect can depend on factors such as:
- Previous repayment history
- Number of active credit accounts
- Existing overdue accounts
- Credit utilisation
- Length of credit history
- Other repayment behaviour
- How the lender reports the account
- Overall credit profile
Therefore, it would be misleading to say that settling a loan will reduce everyone's CIBIL score by a specific number.
Your credit profile is based on multiple factors.
Does a Settled Loan Stay on Your Credit Report?
Credit-report information is maintained according to the applicable credit-bureau reporting framework and the information supplied by lenders.
A settlement does not mean that the account simply disappears from your credit history.
The account may continue to appear with its relevant status and historical information.
This is why borrowers should not assume that paying a settlement amount immediately makes the previous repayment history irrelevant.
If the account information appears incorrect, the borrower can review the credit report and follow the appropriate dispute process with the credit bureau or lender.
How Does Loan Settlement Affect Future Loan Applications?
A lender evaluating a new loan application may review your credit report and repayment history.
A previously settled loan can therefore become relevant when the lender assesses your creditworthiness.
For example, a lender may consider:
- Previous repayment behaviour
- Existing outstanding debt
- Number of active loans
- Credit utilisation
- Previous defaults or overdue accounts
- Account status
- Current income
- Existing financial obligations
- Internal lending policies
A settled account does not automatically mean that you can never obtain another loan.
However, it may influence how a lender evaluates your application.
Each lender has its own underwriting criteria.
Can I Get a Loan After Settling a Personal Loan?
Potentially, yes.
A settled loan does not necessarily mean that you will never be eligible for credit again.
However, future approval depends on the lender and your overall financial and credit profile.
A lender may consider:
- Your current income
- Current employment/business position
- Existing debt
- Repayment history
- Credit report
- Credit score
- Number of recent applications
- Current financial obligations
- Internal eligibility criteria
Therefore, borrowers should focus on building a stronger overall credit profile rather than expecting a particular waiting period to guarantee approval.
How Long Does Loan Settlement Affect Your CIBIL Score?
There is no universal answer that applies to every borrower.
Credit information is based on account history and lender reporting, and the effect of a settlement can depend on the complete credit profile.
It is therefore better to think about settlement as part of your long-term credit history, rather than expecting its impact to disappear after a specific number of days or months.
The important point is that settlement can have longer-term implications, which should be considered before accepting settlement terms.
Can a Settled Loan Be Converted to Closed?
This depends on the lender, account circumstances and whether the lender permits any subsequent change to the account status.
Borrowers should not assume that paying the settlement amount automatically changes a settled account into a closed account.
If you have concerns about the status shown on your credit report, first obtain the relevant account documentation and understand what the lender has reported.
If you believe the information is incorrect, you can raise the issue through the appropriate lender or credit-bureau dispute process.
What Happens to Your Credit Report After Loan Settlement?
After completing a settlement, the lender may update the account information with the credit bureau.
A borrower should then review their credit report after an appropriate reporting cycle to check whether the information is accurate.
Look for details such as:
- Account status
- Outstanding amount
- Payment history
- Account balance
- Date of reporting
- Other account information
If something appears inaccurate, retain the supporting documents and raise the issue through the appropriate process.
What If My Credit Report Shows the Wrong Loan Status?
Credit-report errors can happen.
For example, you may notice:
- Incorrect outstanding balance
- Incorrect payment history
- Wrong account status
- Duplicate account information
- An account that does not belong to you
- Incorrect personal details
If you believe an entry is inaccurate, do not simply ignore it.
Recommended approach:
Step 1: Obtain your latest credit report.
Step 2: Identify the specific incorrect information.
Step 3: Collect supporting documents.
Step 4: Contact the relevant lender if necessary.
Step 5: Raise a dispute through the applicable credit-bureau process.
Step 6: Keep records of your complaint and supporting documents.
Accurate credit reporting is important because future lenders may use credit information as part of their assessment.
Can You Improve Your CIBIL Score After Loan Settlement?
You can work toward improving your overall credit profile after settlement by developing consistent and responsible credit behaviour.
However, no legitimate service can guarantee a specific CIBIL score or a fixed improvement timeline.
The process generally requires patience and consistency.
Some practical areas to focus on include:
Pay Active EMIs on Time
If you have other active loans, make repayments according to their agreed schedules.
Keep Credit Card Balances Manageable
High credit utilisation can be a concern for your credit profile. Avoid allowing revolving balances to become difficult to manage.
Avoid Unnecessary Loan Applications
Applying for multiple loans or credit cards within a short period can result in multiple credit enquiries.
Review Your Credit Report
Regularly check the information associated with your credit accounts.
Correct Errors
If inaccurate information is reported, use the appropriate dispute mechanism.
Avoid Taking Unaffordable Credit
Taking new debt simply to improve your credit score can create additional financial pressure.
Does Paying a Settled Loan Again Improve CIBIL?
This is an important distinction.
Simply paying an amount after settlement does not automatically mean that the account will be reported as though it had originally been repaid in full.
If you have concerns about an account's status, contact the lender and understand the available process based on your specific account.
Do not assume that making an additional payment automatically changes the historical reporting.
Should You Settle a Loan Just to Improve Your Credit Score?
Generally, settlement should not be treated as a credit-score improvement strategy.
Settlement is primarily a debt-resolution option that may be considered when the borrower is unable to manage the original repayment obligations.
If you are comfortably able to repay your loan according to the original agreement, normal repayment and closure may have different credit implications from settlement.
Settlement should therefore be evaluated based on your actual financial circumstances, not simply as a way to change your credit score.
What Is the Difference Between Loan Settlement and Loan Restructuring?
Borrowers sometimes confuse these two options.
Loan Restructuring
Restructuring generally involves changing certain repayment terms so that the borrower can continue servicing the loan under revised conditions.
Depending on the arrangement, this could involve changes to the repayment period or other terms.
Loan Settlement
Settlement involves an agreement to resolve outstanding dues under settlement terms accepted by the lender.
Simple comparison:
|
Loan Restructuring |
Loan Settlement |
|
Aims to make repayment more manageable |
Aims to resolve outstanding dues |
|
Borrower generally continues repayment |
Borrower pays according to settlement terms |
|
Loan terms may be revised |
Settlement terms are agreed |
|
Subject to lender approval |
Subject to lender approval |
|
Credit reporting depends on the arrangement |
May be reported as settled |
The appropriate option depends on the borrower's circumstances.
Is Loan Settlement Better Than Continuing to Pay EMIs?
There is no universal answer.
If you can realistically continue making the contractual payments, maintaining normal repayment may have different consequences from settling the account.
However, if your financial circumstances have changed significantly and continuing repayment is no longer realistic, you may need to evaluate available debt-resolution options.
The decision should consider:
- Current income
- Essential expenses
- Total outstanding debt
- EMI burden
- Account status
- Future borrowing requirements
- Credit implications
- Available alternatives
Avoid making the decision solely based on the settlement amount.
What Should You Consider Before Settling a Loan?
Before accepting settlement terms, consider the following:
1. Your Current Financial Position
Understand exactly how much you can afford.
2. Total Outstanding Debt
If you have multiple loans, consider the complete debt burden.
3. Credit Implications
Understand that settlement may affect your credit profile.
4. Future Borrowing Needs
If you expect to apply for a home loan, vehicle loan or business finance in the future, consider how your credit history may be evaluated.
5. Settlement Documentation
Make sure the settlement terms and payment requirements are properly documented.
6. Payment Channel
Use verified payment channels and retain transaction records.
7. Alternative Solutions
Compare settlement with restructuring, consolidation and other available options.
Does Loan Settlement Affect Credit Card Accounts Too?
Settlement can also be relevant to credit card debt.
Credit cards are revolving credit facilities rather than conventional instalment loans, but settlement can still have implications for how the account is reported.
If you are struggling with multiple credit cards as well as personal loans, it may be useful to evaluate your overall debt situation instead of resolving accounts in isolation.
What If You Have Multiple Settled Accounts?
Having multiple settled accounts can become an important part of your overall credit history.
A lender reviewing a future application may look at your complete credit profile rather than considering one account in isolation.
If multiple accounts have been difficult to manage, the focus should be on preventing further payment problems and establishing sustainable financial habits.
This may include:
- Managing active EMIs carefully
- Avoiding unnecessary borrowing
- Maintaining manageable credit utilisation
- Monitoring credit reports
- Addressing incorrect information
- Building consistent repayment history
Can a Low CIBIL Score Improve After Financial Problems?
Your credit profile can change over time as new repayment information is reported.
However, rebuilding credit is generally a gradual process rather than an instant change.
After a period of financial difficulty, focus on behaviours you can control:
Make payments on time
Payment history is an important component of credit assessment.
Keep debt manageable
Avoid taking on obligations that exceed your repayment capacity.
Monitor your credit report
Review your accounts and identify inaccuracies.
Limit unnecessary credit applications
Apply for credit when there is a genuine financial need and you meet the lender's criteria.
Maintain financial discipline
Consistent behaviour over time is more meaningful than attempting to change your score through short-term actions.
Can Closing Other Loans Help After Settlement?
If you have other loans that are affordable and you repay them according to their agreed terms, maintaining a positive repayment history can contribute to your overall credit profile.
However, closing a loan solely to increase your CIBIL score is not necessarily appropriate.
Credit scoring involves multiple factors, and closing an account does not automatically produce a specific score increase.
The decision to close or retain an account should be based on your overall financial situation and the terms of the credit product.
Does High Credit Card Utilisation Matter After Loan Settlement?
Yes, credit utilisation can be relevant to your credit profile.
If you continue using credit cards heavily after settling a loan, your overall credit position may remain under pressure.
A practical approach is to avoid allowing credit-card balances to grow beyond what you can comfortably repay.
The goal should be sustainable credit management rather than simply trying to achieve a particular score.
What Should You Do If You Want to Rebuild Your Credit Profile?
A practical approach can look like this:
Step 1: Review Your Credit Report
Identify all active, closed, overdue and settled accounts.
Step 2: Verify Account Information
Check whether balances, statuses and payment histories appear accurate.
Step 3: Address Errors
Raise disputes for information that you believe is incorrect.
Step 4: Stabilise Existing Debt
Focus on keeping current accounts manageable.
Step 5: Pay Active Credit Obligations on Time
Avoid creating additional overdue accounts.
Step 6: Avoid Unnecessary Borrowing
Do not take new loans simply to manage an existing credit-score concern.
Step 7: Monitor Progress
Review your credit information periodically and focus on consistent improvement in financial behaviour.
Common Myths About Loan Settlement and CIBIL
Myth 1: "Settlement immediately destroys your CIBIL score."
The effect is not identical for every borrower. Credit profiles contain multiple factors, and the impact depends on individual circumstances and reporting.
Myth 2: "A settled loan disappears from the credit report."
Settlement does not automatically mean the account disappears.
Myth 3: "You can change a settled account to closed simply by paying a small additional amount."
There is no universal rule that automatically changes the reporting status in this way.
Myth 4: "Your CIBIL score will become normal within 30 days."
There is no legitimate universal timeline guaranteeing a specific credit-score recovery.
Myth 5: "You can never get another loan after settlement."
Future credit eligibility depends on the lender and your overall credit and financial profile.
Myth 6: "Settlement is always better than default."
The appropriate debt-resolution option depends on the individual circumstances and should be evaluated carefully.
Loan Settlement and CIBIL: A Simple Example
Consider a borrower who has an outstanding personal loan and has experienced a significant reduction in income.
The borrower can no longer manage the original EMI.
There are several possible situations.
Scenario A: Normal Repayment
The borrower continues paying according to the original agreement.
The account is eventually repaid and closed.
Scenario B: Restructuring
The lender agrees to revised repayment terms.
The borrower continues paying under the new arrangement.
Scenario C: Settlement
The lender agrees to resolve the outstanding account under settlement terms.
The borrower makes the agreed settlement payment and the account is reported according to the applicable arrangement.
These three situations are not identical and can have different financial and credit consequences.
What Happens If You Settle a Loan and Then Apply for a Home Loan?