What Is NPA?
NPA means Non-Performing Asset.
In simple terms, a loan is considered non-performing when the borrower has stopped servicing the repayment obligations according to the applicable schedule for the period specified under the regulatory framework.
For a term loan, RBI's prudential framework defines an NPA as a loan where interest and/or instalment of principal remains overdue for more than 90 days.
The important point is that NPA classification is not the same thing as missing one EMI.
A missed EMI becomes an overdue amount immediately after the due date if it remains unpaid.
The account may then move through stages of stress before reaching NPA classification.
For bank loans, RBI's framework identifies:
- SMA-0
- SMA-1
- SMA-2
- NPA
as part of the early recognition and classification of stressed accounts.
NPA Meaning in Personal Loan: A Simple Explanation
Suppose you have a personal loan with an EMI due on the 5th of every month.
You do not pay the EMI on the due date.
That amount becomes overdue.
If the overdue continues, the account moves into increasingly serious stages of delinquency.
Under the RBI framework for loans other than revolving facilities:
|
Account Stage |
Broad Overdue Period |
|
SMA-0 |
Up to 30 days |
|
SMA-1 |
More than 30 to 60 days |
|
SMA-2 |
More than 60 to 90 days |
|
NPA |
More than 90 days |
RBI's current material describes these SMA categories and the NPA threshold for relevant bank loans.
So, if a personal loan instalment remains unpaid continuously and the applicable conditions are met, the account can eventually be classified as NPA.
Is Every Missed EMI an NPA?
No.
This is one of the most common misconceptions.
Missing one EMI does not automatically mean the loan has become an NPA.
There is a difference between:
Overdue EMI
and
NPA account.
An amount can become overdue from the due date, but NPA classification generally occurs after the applicable overdue period has been reached.
For example:
Day 1
EMI is due but not paid.
The amount is overdue.
Around 30 days
The account may fall into the relevant early-stress category depending on the applicable rules.
31–60 days
The account can fall under SMA-1.
61–90 days
The account can fall under SMA-2.
More than 90 days
The account can be classified as NPA under the applicable framework.
RBI's rules require classification to be performed based on the relevant day-end process and the account's overdue status.
What Is SMA Before NPA?
SMA means Special Mention Account.
It is used to identify signs of financial stress before the account becomes an NPA.
The purpose is important.
The idea is to identify stressed accounts early rather than waiting until the account becomes severely delinquent.
For relevant loans, the categories are broadly:
SMA-0
Up to 30 days overdue.
SMA-1
More than 30 days and up to 60 days overdue.
SMA-2
More than 60 days and up to 90 days overdue.
NPA
More than 90 days overdue for a term loan under the applicable framework.
RBI specifically states that SMA classification applies to retail loans as well under the relevant bank framework.
This means borrowers should not wait for the loan to become NPA before taking the problem seriously.
SMA-1 and SMA-2 should be treated as warning stages.
How Does a Personal Loan Become NPA?
Consider this example.
Rahul has a personal loan EMI of ₹18,000.
His EMI is due on 10 January.
He does not pay it.
The amount becomes overdue.
If he continues to remain unpaid:
- The overdue period increases.
- The lender may contact him.
- The account can move into relevant SMA classification.
- Credit reporting may reflect the payment delay.
- Recovery communication may increase.
- If the overdue crosses the applicable NPA threshold, the account can be classified as NPA.
The exact dates and classification depend on the lender's system, applicable regulatory rules and the account's repayment status.
RBI's framework states that banks should identify the overdue date through their day-end process and classify SMA/NPA based on the account's status on the relevant date.
What Happens When a Personal Loan Becomes NPA?
An NPA classification can create several consequences for the borrower.
These may include:
1. Credit-report impact
Missed payments and overdue amounts can negatively affect your credit profile.
2. Increased recovery communication
The lender may intensify its efforts to recover the outstanding amount.
3. Difficulty obtaining new credit
Future lenders may view recent defaults or overdue accounts as signs of financial stress.
4. Possible legal communication
Depending on the circumstances, lender policy and applicable law, borrowers may receive formal notices or other legal communication.
5. Difficulty managing multiple debts
If you have several loans, an NPA can be a sign that the overall debt burden has become unsustainable.
6. Need for a structured resolution
At this stage, simply ignoring the lender generally does not resolve the underlying liability.
Does NPA Affect Your CIBIL Score?
Yes, serious loan delinquency can negatively affect your credit profile.
Your CIBIL Report contains information about your loan accounts and repayment behaviour as reported by lenders.
CIBIL explains that the payment history, outstanding amounts and days past due are among the information used in the credit report and that missed payments can negatively affect creditworthiness.
CIBIL also states that its report includes account information such as:
- Loan type
- Lender name
- Account number
- Date opened
- Date closed
- Current balance
- Payment information
- Month-on-month repayment history
and other account details.
Therefore, if your personal loan becomes seriously overdue, the consequences can extend beyond the current loan.
Your future access to credit may also become more difficult.
Does NPA Automatically Mean “CIBIL Default”?
Borrowers often use these terms interchangeably, but they are not exactly the same thing.
NPA is an asset-classification concept used by lenders under applicable prudential rules.
CIBIL reporting is the reporting of credit information to a credit information company.
Your credit report can contain detailed repayment information, including days past due and account status.
CIBIL itself states that it does not maintain a separate “defaulters list.” It maintains credit histories reported by banks and financial institutions.
So rather than asking:
“Am I on the CIBIL defaulter list?”
it is more useful to ask:
“What is my lender reporting about this account in my credit report?”
How Does NPA Affect Future Loan Approval?
A serious overdue or NPA-related history can make borrowing more difficult.
When assessing a loan application, lenders may look at:
- Credit score
- Repayment history
- Current overdue amounts
- Existing loans
- Credit utilisation
- Recent credit enquiries
- Income
- Employment or business stability
- Debt burden
- Account status
CIBIL states that missed payments, overdue amounts and settled accounts in the recent past can indicate financial distress and may contribute to loan rejection.
However, there is no universal rule that says:
“If your loan becomes NPA, you can never get another loan.”
Loan approval is ultimately determined by the lender's own credit policy and the applicant's complete financial profile.
Does an NPA Mean the Loan Is Cancelled?
No.
This is extremely important.
An NPA classification does not mean:
- The loan disappears
- The borrower no longer owes money
- Interest and other applicable charges automatically disappear
- The lender cannot pursue recovery
- The account becomes automatically settled
- The borrower is released from the contractual obligation
NPA is a classification of the loan account.
It does not automatically cancel the underlying debt.
The borrower should therefore not assume:
“My loan has become NPA, so I don't have to pay it anymore.”
That is incorrect.
Does NPA Mean the Bank Has Written Off the Loan?
No.
NPA and write-off are different concepts.
A loan can be classified as NPA without being written off.
A write-off is an accounting treatment used by a lender under applicable rules and policies.
Even where a lender has written off an amount for accounting purposes, that does not automatically mean the borrower's underlying liability disappears.
CIBIL's guidance distinguishes between settled and written-off account statuses and notes that written-off, settled and suit-filed cases are not viewed favourably by lenders.
Therefore:
NPA ≠ Write-off
and:
Write-off ≠ Automatic cancellation of the borrower's liability.
NPA vs Default: What Is the Difference?
These terms are related but should not be treated as identical.
Default
Generally refers to failure to meet a repayment obligation.
For example:
EMI was due but not paid.
NPA
A formal classification applied when the account meets the applicable regulatory criteria for non-performance.
For a typical term loan, the RBI framework uses the more-than-90-days overdue threshold.
Therefore:
A borrower can be in default/overdue status before the loan becomes an NPA.
This is why early action matters.
NPA vs SMA: What Is the Difference?
Think of SMA as a warning stage.
NPA is a more serious classification.
|
Feature |
SMA |
NPA |
|
Purpose |
Early identification of stress |
Classification of non-performing account |
|
Stage |
Before NPA |
After applicable NPA threshold |
|
Typical term-loan timeline |
Up to 90 days |
More than 90 days |
|
Borrower action |
Immediate corrective action |
Structured resolution becomes increasingly important |
|
Credit consequences |
Can already reflect payment problems |
Serious delinquency may significantly affect credit profile |
RBI's framework specifically uses SMA-0, SMA-1 and SMA-2 categories to identify stress before NPA classification.
Can an NPA Loan Be Repaid?
Yes.
An NPA account can potentially be regularised or resolved, depending on the account, lender policies and applicable rules.
The borrower should first determine:
- Total outstanding
- Overdue amount
- Interest and charges
- Account status
- Amount required to regularise
- Whether restructuring is available
- Whether settlement can be considered
- Whether legal proceedings have started
Do not rely on an assumption that the account is beyond repair simply because it has become NPA.
Can an NPA Account Become Standard Again?
Potentially, yes, depending on the applicable regulatory framework and the lender's requirements.
For bank loans, RBI's framework provides conditions for upgrading an NPA account. The current bank master circular states that an NPA account can be upgraded to standard when the entire arrears of interest and principal are paid.
This is an important point.
If you are trying to regularise an NPA, ask the lender exactly:
- What amount must be paid?
- What arrears are outstanding?
- What documentation is required?
- When will the account status be updated?
- How will the credit information be reported?
Do not assume that paying one EMI automatically converts an NPA back to standard status.
Can You Restructure a Personal Loan After It Becomes NPA?
This depends on the lender, account status, applicable policies and regulatory requirements.
Restructuring generally means changing repayment terms to make the debt more manageable.
Possible changes may include:
- Revised repayment schedule
- Longer tenure
- Modified EMI
- Other permitted restructuring terms
But restructuring is not an automatic right.
The lender must evaluate the account and decide whether restructuring is appropriate.
If you are approaching NPA status, it is generally better to discuss available options before the situation becomes more difficult, rather than waiting indefinitely.
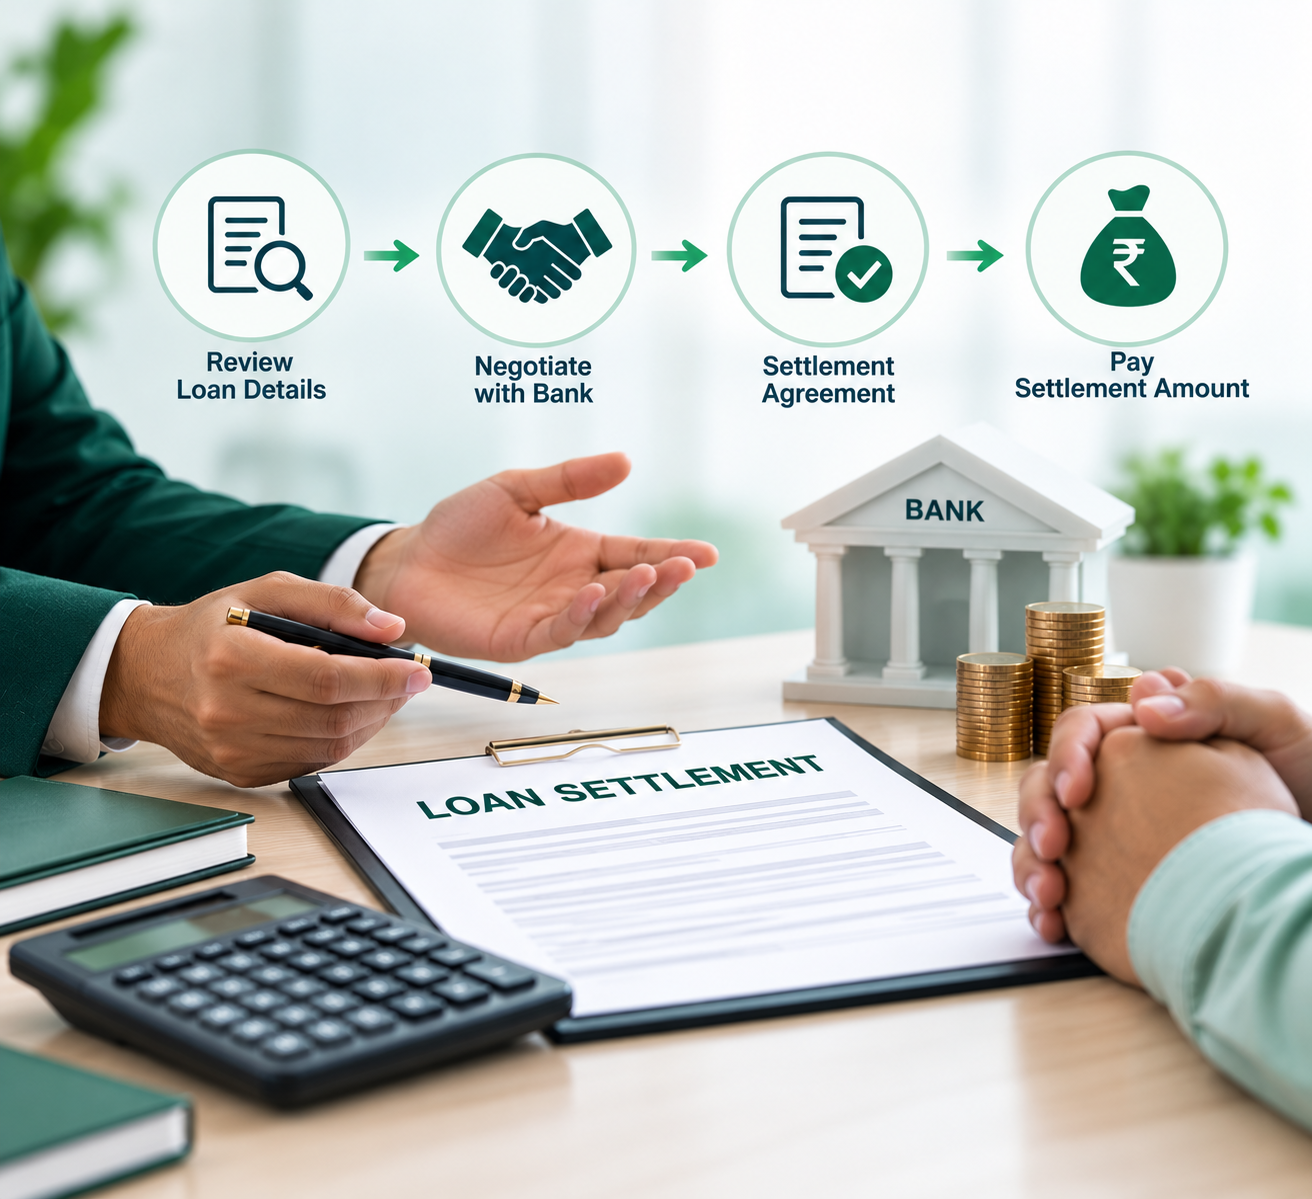
NPA and Loan Settlement: Can an NPA Loan Be Settled?
An NPA account may be considered for settlement, but settlement is not automatic.
A settlement involves an agreement with the lender to accept a specified amount to resolve the outstanding liability, subject to the lender's approval and applicable rules.
RBI's compromise-settlement framework recognises compromise settlements as a resolution mechanism for stressed accounts and requires regulated entities to have board-approved policies governing such settlements.
However, borrowers should understand an important distinction:
Settlement is not the same as full repayment.
If a lender accepts less than the total amount due, the account may be reported as settled rather than closed.
CIBIL explains that a “settled” status indicates partial payment made with the lender's consent against the total outstanding and that such status is not viewed favourably by lenders.
Does NPA Settlement Remove the NPA From CIBIL?
Not automatically.
Settlement resolves the debt according to the settlement terms, but it does not necessarily erase the historical repayment information.
The account may be reported as:
Settled
rather than:
Closed
This distinction can matter when you apply for future credit.
CIBIL has specifically explained that settled accounts can affect access to credit and has published examples where a lender rejected a loan application because a previous personal loan was reported as settled rather than closed.
Therefore, borrowers should understand the credit implications before agreeing to settlement.
What If You Cannot Pay the Full NPA Amount?
If you cannot afford the entire outstanding amount, do not simply stop communicating with the lender.
Instead, prepare a realistic financial assessment.
Calculate:
Your income
- Salary
- Business income
- Other regular income
Essential expenses
- Rent
- Food
- Utilities
- Education
- Medical expenses
- Household expenses
Existing debt
- Personal loans
- Credit cards
- App-based loans
- Business loans
- Other financial obligations
Available funds
- Savings
- Liquid investments
- Family support, if genuinely available
- Other legitimate sources of funds
This will help determine whether you have:
temporary repayment difficulty
or
long-term debt affordability problems.
What Should You Do If Your Personal Loan Is About to Become NPA?
If you are currently between 30 and 90 days overdue, do not wait for the account to become NPA before taking action.
Step 1: Confirm the overdue amount
Ask the lender for an updated statement.
Step 2: Understand the account status
Find out whether the account is currently:
- Regular
- SMA-1
- SMA-2
- NPA
Step 3: Calculate your repayment capacity
Determine what you can realistically afford.
Step 4: Contact the lender
Explain the financial difficulty.
Step 5: Ask about available options
Depending on your circumstances, these may include:
- Regular repayment
- Restructuring
- Rescheduling