Why Is Reducing Expenses Important When You Have Debt?
When you have outstanding loans or credit card dues, every month matters.
A large portion of your income may already be committed to fixed repayments. If your spending is not properly managed, you may end up using credit cards or short-term loans to cover everyday expenses.
This can create a cycle in which new borrowing is used to manage old borrowing.
Reducing unnecessary expenses can help in several ways.
1. More Money Becomes Available for Repayment
When you identify and reduce avoidable spending, you may be able to redirect some of that money towards existing loan or credit card obligations.
Even a modest monthly saving can make a difference when maintained consistently.
2. You Can Reduce Additional Borrowing
A well-planned budget helps you understand how much money is available for essential expenses.
This can reduce the need to depend on credit cards or short-term loans for routine purchases.
3. You Gain Better Control Over Your Finances
Knowing exactly where your money goes can make financial decisions easier.
Instead of worrying about multiple bills without a clear plan, you can prioritise payments and plan upcoming expenses.
4. You Can Build Financial Resilience
Once your monthly expenses become more manageable, you can gradually work towards creating an emergency savings buffer.
This can help you handle unexpected expenses without immediately relying on additional borrowing.
12 Practical Ways to Reduce Monthly Expenses When in Debt
Reducing expenses does not mean eliminating everything you enjoy. It means identifying spending that can be adjusted without affecting essential needs.
Here are 12 practical approaches.
1. Prepare a Detailed Monthly Budget
Start by listing your monthly take-home income.
Then divide your expenses into different categories:
Fixed expenses
- House rent or home loan EMI.
- Personal loan EMIs.
- School or college fees.
- Insurance premiums.
- Essential subscriptions and bills.
Variable expenses
- Groceries.
- Fuel and transportation.
- Electricity and water.
- Dining out.
- Shopping.
- Entertainment.
Financial commitments
- Credit card payments.
- Other loan repayments.
- Existing overdue amounts.
- Savings and emergency contributions.
Once everything is listed, calculate how much money remains after essential expenses and debt obligations.
This gives you a realistic starting point for reducing spending.
2. Review Your Credit Card Spending
Credit cards can make purchases convenient, but uncontrolled usage can increase financial pressure.
Review your recent statements and identify spending that could have been avoided.
Look for:
- Frequent food delivery orders.
- Unplanned online purchases.
- Repeated shopping transactions.
- Unnecessary subscriptions.
- Purchases made without considering repayment capacity.
If you are already carrying a credit card balance, avoid adding new discretionary spending wherever possible.
Paying only the minimum amount due can leave a substantial balance outstanding, potentially attracting further interest and charges.
Whenever possible, pay the full statement balance by the due date.
3. Reduce Food Delivery and Dining Expenses
Food-related spending can become a significant monthly expense when small transactions are repeated frequently.
For example, consider a household spending ₹250 on food delivery four times a week.
That comes to approximately ₹4,000 per month.
Reducing the frequency of these orders and planning meals at home could free up some money for other priorities.
Practical ideas include:
- Prepare a weekly meal plan.
- Carry homemade lunch to work.
- Purchase groceries using a planned list.
- Avoid ordering food out of convenience.
- Set a reasonable monthly dining budget.
The goal is not to stop enjoying food outside. It is to make the spending intentional.
4. Review Subscriptions and Recurring Payments
Small recurring charges can quietly consume a portion of your monthly income.
Check your bank statements and payment applications for:
- Multiple OTT subscriptions.
- Unused gym memberships.
- Premium mobile applications.
- Duplicate cloud-storage plans.
- Unused online services.
- Memberships you rarely use.
Cancel services that do not provide sufficient value.
Even small savings become useful when combined over several months.
5. Plan Grocery Shopping in Advance
Unplanned grocery purchases often result in unnecessary spending.
Before visiting a supermarket or placing an online order, prepare a shopping list based on actual household requirements.
Try these practices:
- Purchase frequently used essentials in planned quantities.
- Compare prices across stores.
- Avoid buying products simply because they are discounted.
- Reduce food wastage.
- Track grocery spending every week.
A discount is not a saving if you purchase something you did not need.
6. Review Transportation Costs
Daily travel can take up a meaningful part of a monthly budget.
Look at your regular transportation expenses and identify opportunities to reduce them.
Depending on your circumstances, consider:
- Using public transportation.
- Sharing rides with colleagues.
- Combining multiple errands into one trip.
- Planning routes to reduce unnecessary travel.
- Comparing the cost of private transport with public alternatives.
Do not compromise safety or essential travel requirements just to save a small amount.
7. Compare Utility and Mobile Bills
Electricity, internet, mobile and other household bills should be reviewed periodically.
Check whether your current plans match your actual usage.
You may be able to save money by:
- Switching to a more suitable mobile plan.
- Avoiding duplicate internet services.
- Turning off unused electrical equipment.
- Using energy-efficient appliances where practical.
- Reviewing unnecessary add-on services.
Avoid cancelling essential connectivity or utilities if they are required for work, education or household needs.
8. Avoid Unplanned Shopping
Impulse purchases can disturb even a carefully prepared budget.
Before making a non-essential purchase, ask yourself:
- Do I actually need this item?
- Can the purchase wait?
- Is there a more affordable alternative?
- Will this expense affect my upcoming EMI payment?
One useful habit is to wait 24 hours before making non-essential online purchases.
This gives you time to reconsider whether the expense is necessary.
9. Review Insurance and Financial Products
Insurance is an important part of financial protection, but it is worth reviewing whether your existing policies and financial products are suitable for your circumstances.
Check:
- Premium amounts.
- Policy coverage.
- Renewal dates.
- Duplicate coverage.
- Unnecessary add-on products.
Do not cancel essential health, life or other protection solely to reduce monthly expenses without understanding the consequences.
10. Plan Major Purchases Instead of Using Credit Immediately
Buying electronics, furniture or household appliances through credit can increase your monthly obligations.
Before making a large purchase, consider whether it can be postponed or funded through planned savings.
If an EMI option is available, compare the total payable amount, interest, processing fees and tenure.
A smaller monthly instalment does not always mean a cheaper purchase.
11. Set a Weekly Spending Limit
A monthly budget can sometimes feel difficult to follow because it covers too many days.
Dividing discretionary spending into weekly limits can make it easier to monitor.
For example, if your monthly discretionary budget is ₹4,000, you could plan approximately ₹1,000 per week.
Track your spending throughout the week and adjust if necessary.
Keep essential expenses and contractual loan repayments separate from this discretionary limit.
12. Avoid Taking New Loans to Cover Everyday Expenses
One of the most important financial habits when dealing with debt is to avoid unnecessary new borrowing.
Using a new personal loan, credit card cash advance or app-based loan to cover regular household expenses may provide temporary relief but can create additional repayment obligations.
Before borrowing again, review your income, existing EMIs and available repayment alternatives.
If your existing repayments are already unaffordable, adding another EMI may make the situation more difficult.
How to Create a Monthly Budget When You Have Multiple EMIs
A budget for someone managing multiple loans should give priority to essential household requirements and existing financial obligations.
Consider the following illustrative example.
Monthly Budget Example: ₹50,000 Take-Home Income
|
Expense category |
Monthly allocation |
|
House rent |
₹10,000 |
|
Groceries and household needs |
₹7,000 |
|
Utilities and mobile bills |
₹2,500 |
|
Transportation |
₹3,000 |
|
Medical and essential expenses |
₹2,500 |
|
Loan and credit card repayments |
₹15,000 |
|
Personal and discretionary spending |
₹3,000 |
|
Emergency savings |
₹2,000 |
|
Other planned expenses |
₹5,000 |
|
Total |
₹50,000 |
<text color="secondary" size="xs">Illustrative example only. Actual allocations should reflect household size, location, contractual obligations and essential expenses.</text>
The most important step is to make sure that your planned expenses do not exceed your take-home income.
If your EMIs already consume a large portion of your salary, reducing small discretionary expenses alone may not be enough.
You may also need to review your repayment arrangements with your lenders.
Which Expenses Should You Reduce First When You Have Debt?
Not every expense should be treated equally.
A practical way to prioritise is to separate spending into three groups.
|
Category |
Examples |
Recommended approach |
|
Essential |
Rent, food, utilities, medicine |
Protect these expenses |
|
Adjustable |
Dining, shopping, entertainment, subscriptions |
Review and reduce where practical |
|
Financial obligations |
EMIs, credit card dues, overdue payments |
Plan carefully and communicate with lenders |
Do not skip essential medication, education requirements or necessary household spending to make an unrealistic repayment commitment.
The objective is to create a sustainable budget, not simply the smallest possible budget.
How Can You Use Savings to Repay Debt Faster?
Once you identify expenses that can be reduced, decide how the available money should be used.
Two commonly used debt repayment methods can help borrowers prioritise their obligations.
1. Debt Avalanche Method
Under the avalanche method, you prioritise the debt carrying the highest interest rate.
Continue making the required payments on your other accounts and direct available extra repayment money towards the highest-interest debt.
Once that debt is cleared, move to the next highest-interest obligation.
This approach can reduce total interest costs when followed consistently.
2. Debt Snowball Method
Under the snowball method, you prioritise the smallest outstanding debt first.
After clearing it, move towards the next smallest balance.
This approach can provide a sense of progress and motivation, although it may not minimise total interest costs.
Which Method Is Better?
The avalanche method is generally more cost-efficient when the objective is to reduce interest expenditure.
The snowball method may be easier for some borrowers to follow because smaller balances are cleared sooner.
Choose the approach that matches your financial circumstances and that you can maintain consistently.
Continue meeting all required payment obligations while following either strategy.
What If Your Monthly EMI Is Too High Even After Reducing Expenses?
Sometimes the problem is not discretionary spending.
A borrower may already be following a strict budget but still struggle because multiple EMIs consume most of their monthly income.
For example:
- Monthly take-home income: ₹40,000.
- Combined loan EMIs: ₹22,000.
- Rent and essential household expenses: ₹15,000.
- Remaining amount: ₹3,000.
In this situation, there may be very little room for savings, unexpected expenses or additional repayment.
Further reducing essential expenses may not be realistic.
Instead, the borrower should review the complete debt situation and explore appropriate options.
1. Contact Your Lenders
Explain your repayment difficulties and ask whether any suitable repayment arrangements are available.
Do not ignore communication about overdue accounts.
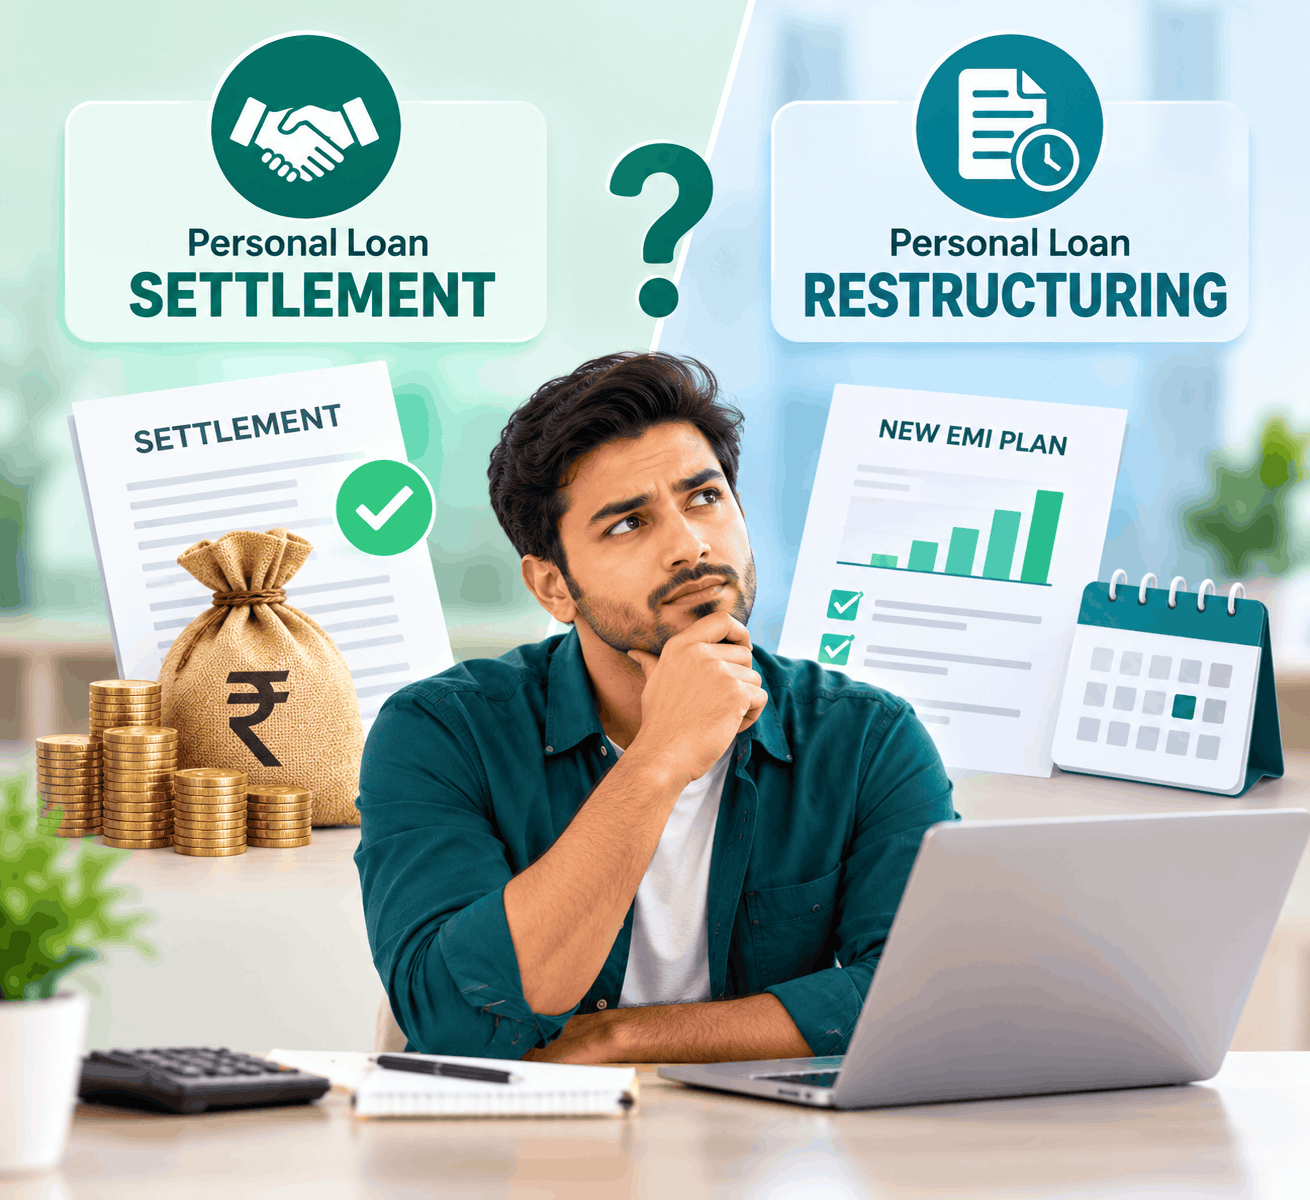
2. Explore Loan Restructuring
Depending on the lender's policies and your account circumstances, restructuring or revised repayment terms may be available.
Understand the revised interest cost, tenure and total amount payable before accepting.
3. Consider Debt Consolidation
If you have several loans and can still afford repayments, debt consolidation may help combine eligible obligations into a single repayment facility.
Compare the total cost of the new loan with your existing debts before proceeding.
4. Understand Loan Settlement
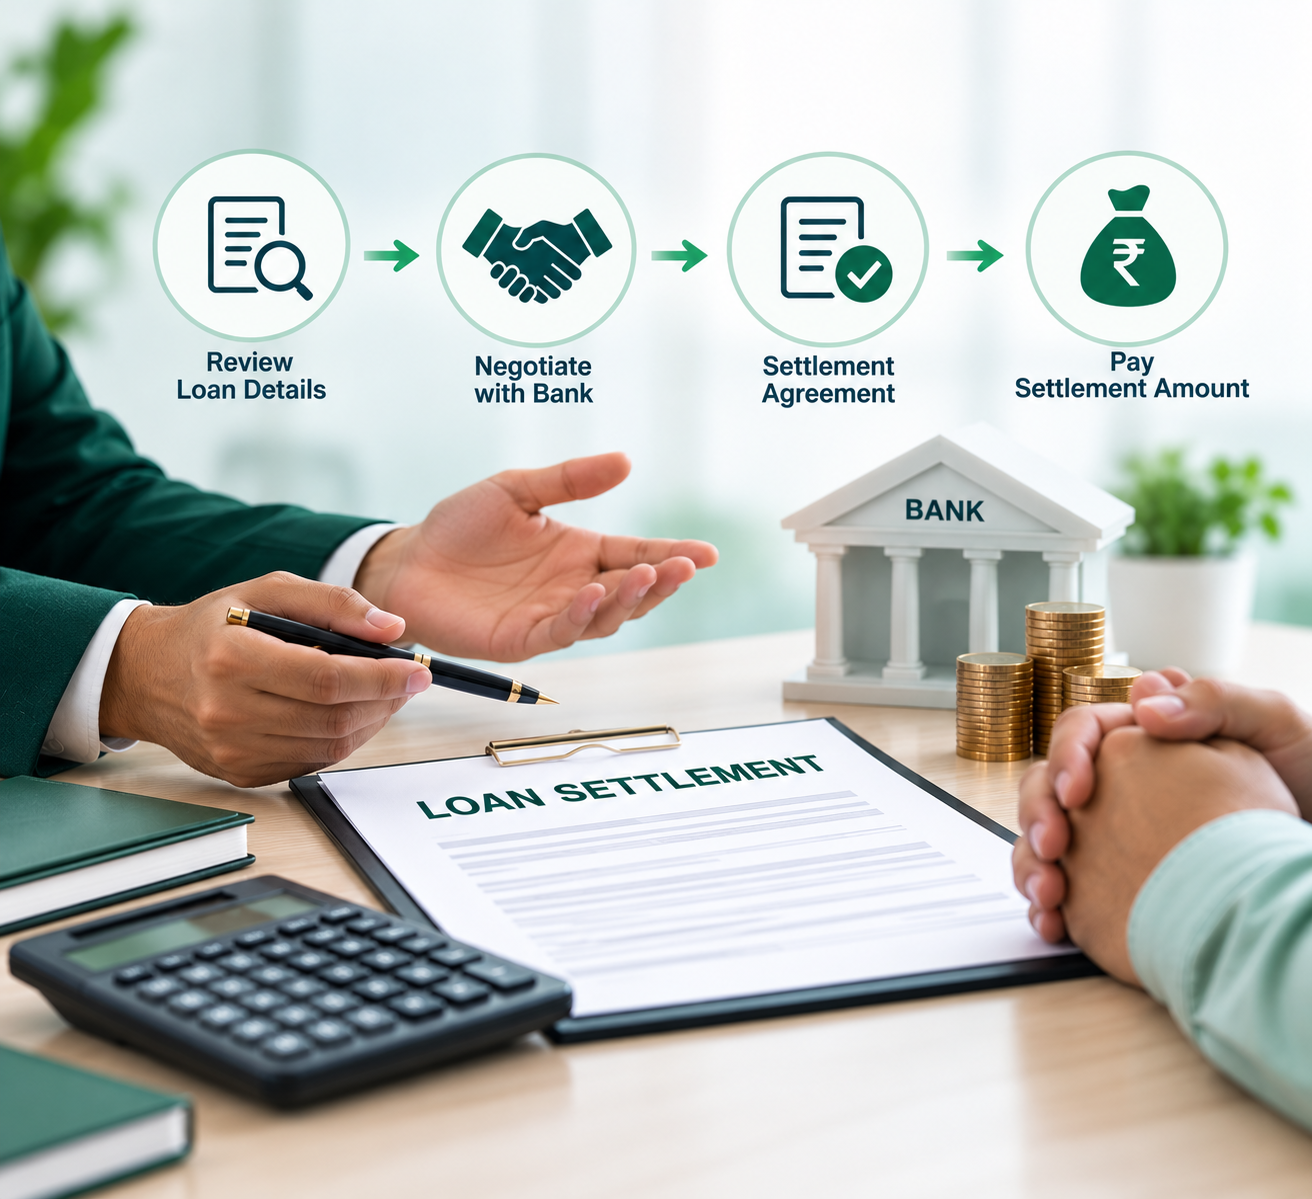
If genuine financial hardship makes full repayment unrealistic, you may approach your lender to discuss a possible compromise settlement.
The lender may consider accepting an agreed amount to resolve the outstanding debt.
However, settlement is subject to lender approval and can negatively affect your credit profile.
It should not be considered a guaranteed way to reduce debt.
Common Mistakes to Avoid When Reducing Expenses
While trying to manage debt, avoid these common financial mistakes.
Cutting essential expenses: Do not compromise necessary food, healthcare, education or safety requirements.
Paying only minimum credit card dues indefinitely: This may leave a substantial balance outstanding and increase interest costs.
Taking another loan without calculating the total cost: New borrowing may increase your overall repayment burden.
Ignoring loan statements: Always understand your current outstanding balance and payment obligations.
Cancelling important insurance without review: This may expose you to significant financial risks.
Following an unrealistic budget: A budget that does not account for actual household needs is difficult to maintain.
Ignoring communication from lenders: Maintain appropriate communication and understand the options available.
How ReducedDebts Helps Borrowers Understand Their Debt Situation
Reducing expenses is an important step towards managing debt, but budgeting alone may not solve every financial difficulty.
If a borrower is struggling with multiple loan EMIs, credit card balances, overdue accounts or recovery pressure, it may be useful to understand the complete debt position before deciding what to do next.
ReducedDebts is a debt resolution and loan settlement platform in India helping individuals and businesses navigate financial difficulties related to outstanding loans and credit obligations.
Areas of guidance include:
- Personal loan settlement.
- Credit card settlement.
- Loan settlement.
- Debt management.
- Debt consolidation.
- EMI-related guidance.
- App loan debt resolution.
- Recovery support.
- Business debt solutions.
Our approach focuses on understanding the borrower's circumstances, explaining available options and supporting informed financial decisions.
Not every borrower needs settlement. Depending on repayment capacity, budgeting, restructuring or consolidation may be more appropriate.
Where settlement is considered, the outcome remains subject to the respective lender's policies and approval.
If your monthly repayments have become difficult to manage, visit ReducedDebts to understand your available debt-resolution options.
Final Thoughts
Reducing monthly expenses is one of the practical steps towards managing debt, but it requires more than simply spending less.
The real objective is to understand your financial priorities, protect essential household needs and create a repayment plan that you can maintain.
Start with small changes. Review your spending every month, avoid unnecessary borrowing and direct available savings towards your financial obligations.
If your EMIs remain unaffordable even after careful budgeting, consider discussing suitable repayment options with your lenders.
Financial stability begins when you understand where your money goes and make informed decisions about where it should go next.
Disclaimer: This article is for general educational and informational purposes only and does not constitute financial or legal advice. ReducedDebts is not a lender or a law firm. Repayment restructuring, debt consolidation and compromise settlement depend on individual circumstances and lender approval. No debt reduction, settlement amount or credit-score improvement is guaranteed. Review your financial obligations and applicable lender terms before making decisions.