Credit card payments can become difficult to manage when financial circumstances change unexpectedly. A job loss, business disruption, medical emergency or increasing household expenses can make regular repayments challenging.
For borrowers using Punjab National Bank (PNB) credit cards, unpaid balances can lead to overdue charges, recovery communication and concerns about their credit history.
When repayment becomes difficult, borrowers often search for information about PNB credit card settlement, One-Time Settlement (OTS), eligibility, settlement amounts and CIBIL score implications.
But does PNB offer credit card settlement? When can an account be considered for OTS? Is there a fixed settlement percentage? And how does a settled credit card account affect future borrowing?
This guide explains the PNB credit card settlement process, important points from the bank's published policy, possible alternatives and precautions borrowers should understand before making a decision.
What Is PNB Credit Card Settlement?
PNB credit card settlement is a negotiated arrangement in which Punjab National Bank may agree to accept an approved amount to resolve an outstanding credit card account.
This arrangement is commonly known as One-Time Settlement (OTS) or compromise settlement.
In certain circumstances, the bank may consider accepting an amount lower than the total outstanding dues. The final amount and conditions depend on the bank's assessment and applicable policy.
PNB's published Credit Card Business Policy specifically includes provisions for compromise settlement and OTS in respect of credit card accounts.
The policy describes OTS as a recovery mechanism used on the merits of individual cases, particularly in relation to NPA credit card accounts.
Important: Settlement is not automatically available to every cardholder. The bank decides whether an account qualifies and whether to approve the proposed arrangement.
Does Punjab National Bank Offer Credit Card OTS?
Yes. PNB's published Credit Card Business Policy includes a dedicated provision for One-Time Settlement of credit card accounts.
The policy explains that OTS is used as a recovery mechanism for the bank's increasing NPA credit card portfolio.
It also refers to separate operational guidelines covering:
- Eligible credit card accounts.
- OTS in certain NPA credit card cases.
- Calculation of memorandum dues.
- Settlement formula.
- Payment terms.
This is an important distinction: the public policy confirms that PNB has an OTS framework, but it does not mean every borrower is entitled to settlement or that a single settlement formula applies to every account.
The bank evaluates the case under its applicable operational guidelines and approval process.
When Can a PNB Credit Card Account Become Eligible for OTS?
A borrower should understand the difference between an overdue credit card account and an NPA account.
PNB's published credit card policy identifies the following account categories:
- Standard credit card account.
- Delinquent or irregular account.
- Non-performing asset (NPA) account.
The policy divides overdue accounts into delinquency stages based on the period of financial irregularity.
An account that remains unpaid for a longer period may progress through the applicable delinquency classification process and eventually enter the NPA category under the bank's rules.
PNB's policy specifically identifies OTS as a recovery tool for NPA credit card accounts.
However, borrowers should not assume that reaching a particular overdue period automatically guarantees settlement approval.
The bank evaluates eligible accounts on their individual merits.
What Financial Circumstances May Lead a Borrower to Request Settlement?
A borrower may approach PNB to explain genuine repayment difficulties arising from circumstances such as:
- Loss of employment.
- Reduced monthly income.
- Business losses.
- Medical emergencies.
- Unexpected family expenses.
- Multiple outstanding loans.
- Inability to manage increasing credit card balances.
These circumstances can help explain why regular repayment has become difficult. However, they do not guarantee that the bank will approve an OTS request.
PNB Credit Card Settlement Percentage: How Much Can You Pay?
One of the most common questions is: What percentage does PNB accept for credit card settlement?
There is no single publicly guaranteed settlement percentage for every PNB credit card account.
The bank's published policy refers to operational guidelines for settlement calculations and payment conditions. The actual offer depends on the applicable policy and the bank's assessment of the account.
Factors that may be considered include:
1. Outstanding credit card dues
The bank reviews the amount outstanding and the applicable account-related charges.
2. Account classification
The current status of the account and its delinquency history may be relevant.
3. Financial circumstances
The borrower's income, repayment capacity and supporting documents may be considered.
4. Recovery prospects
The bank may evaluate the available recovery options and the merits of a compromise arrangement.
5. Bank approval
The settlement amount and conditions require approval through the bank's applicable process.
Should You Trust a Fixed PNB Settlement Percentage?
Be cautious about advertisements or individuals promising a guaranteed percentage of PNB credit card settlement.
Another cardholder's settlement amount does not establish what PNB will offer in your case.
Always obtain the written settlement offer and verify it through official bank channels before making any payment.
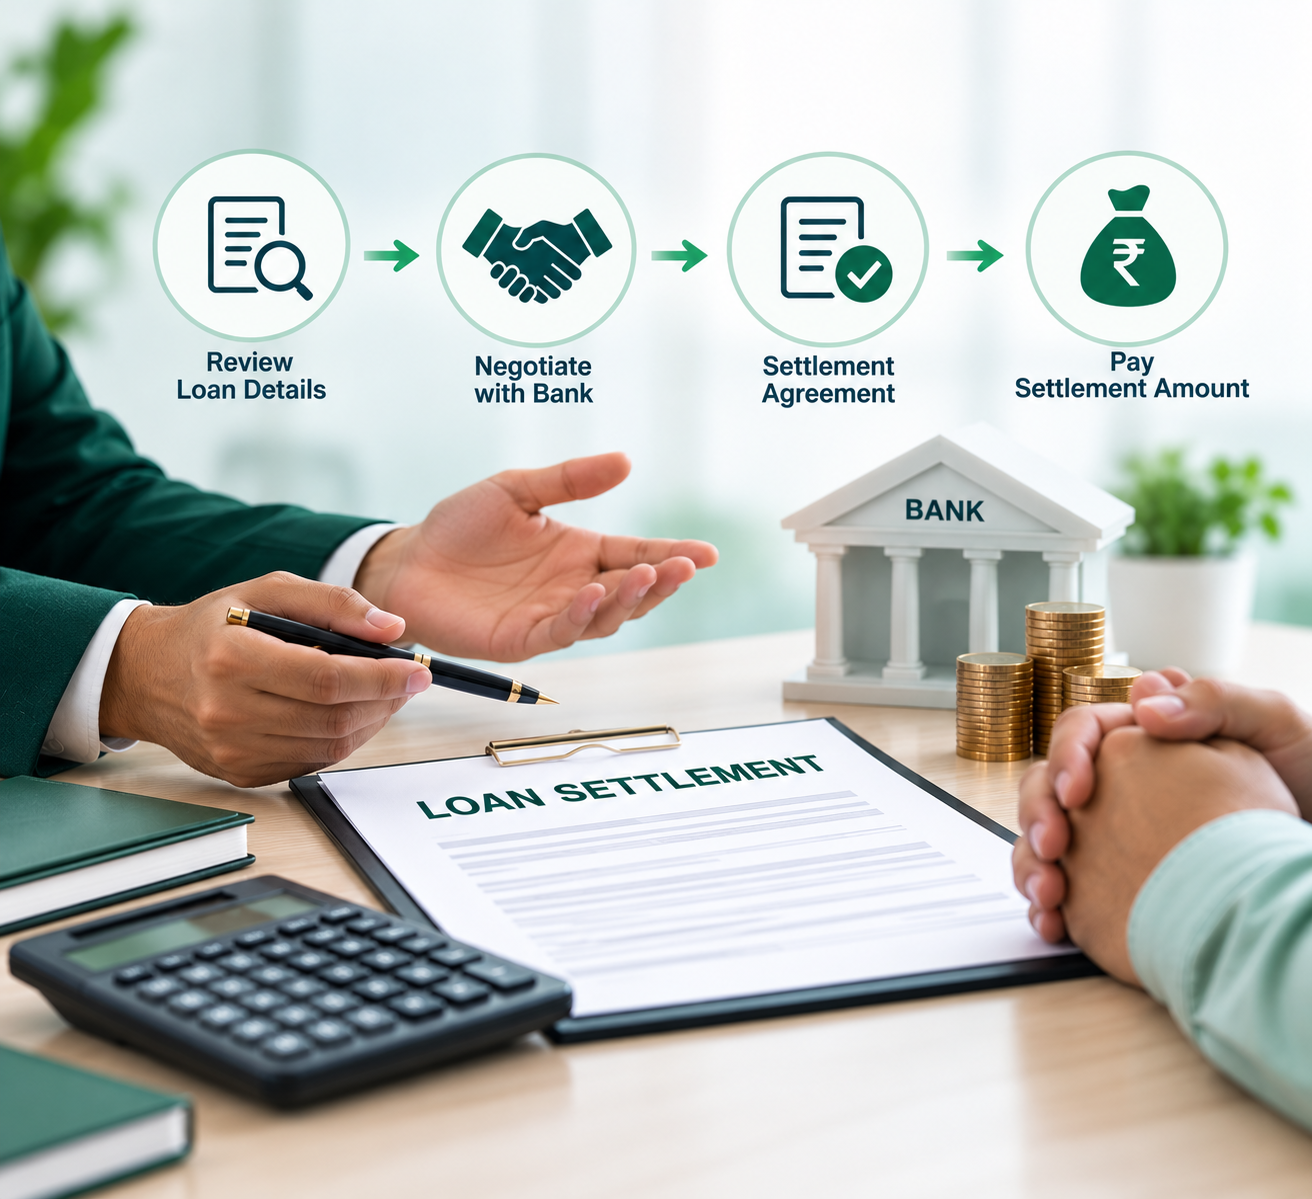
PNB Credit Card Settlement Process: Step-by-Step
If you are struggling to repay your PNB credit card dues, follow a structured approach.
Step 1: Review Your Outstanding Credit Card Balance
Start by checking your latest PNB credit card statement.
Review:
- Total outstanding amount.
- Minimum amount due.
- Overdue balance.
- Interest and applicable charges.
- Previous payment history.
- Any pending transaction disputes.
This will help you understand your actual financial obligation.
Step 2: Assess Your Financial Position
Prepare a realistic assessment of your income and expenses.
Include your monthly salary or business income, household expenses, existing loan EMIs, other credit card dues and any exceptional financial commitments.
Determine how much you can realistically arrange without creating additional financial pressure.
Step 3: Contact PNB Through Official Channels
Approach Punjab National Bank or its authorised credit-card service channels.
Explain why you are unable to maintain regular repayments and ask about the available options for your account.
You may enquire about:
- Regular repayment arrangements.
- Eligible EMI facilities.
- Other repayment solutions.
- Restructuring, where available.
- Compromise settlement or OTS, if applicable.
PNB's official credit-card portal provides customer support and grievance-related information.
Step 4: Explain Your Financial Hardship
If you want the bank to consider your account for a possible settlement, explain your financial circumstances clearly.
For example, mention whether your repayment difficulty is related to:
- Job loss.
- Business disruption.
- Reduced income.
- Medical expenses.
- Other genuine financial difficulties.
Provide supporting documents when requested.
Step 5: Wait for the Bank's Assessment
The bank evaluates the account under its applicable policies and operational guidelines.
Do not assume that an OTS request has been approved simply because a representative has discussed settlement with you.
The bank's written approval is important.
Step 6: Review the OTS Offer
If PNB approves a settlement, carefully review the written offer.
Check:
- Approved settlement amount.
- Payment deadline.
- Instalment conditions, if permitted.
- Payment instructions.
- Conditions for completing the settlement.
- Consequences of missing an agreed payment.
- Credit-reporting implications.
Make sure you understand the complete agreement before accepting it.
Step 7: Make Payment Through Verified Channels
Use only the official payment instructions stated in the verified settlement communication.
Never transfer settlement money to a personal UPI ID, QR code or individual bank account based on verbal assurances.
Keep the payment receipt and transaction reference.
Step 8: Obtain Settlement Confirmation
After completing the agreed payment, obtain written confirmation from the bank.
Preserve the settlement letter, payment receipts and all relevant communication.
Later, review your credit report to verify that the account has been updated accurately.
What Is PNB's Policy on Credit Bureau Reporting After OTS?
This is one of the most important aspects of PNB credit card settlement.
PNB's published Credit Card Business Policy specifically states that when an NPA credit card account is closed under OTS, its status is updated with credit information companies as "Settled."
The policy also discusses cases in which cardholders request that the credit bureau record be changed from "Settled" to a normal closure status.
This confirms that paying the agreed OTS amount does not automatically mean the account will be reported as fully paid or normally closed.
Settled vs Closed: What Is the Difference?
|
Settled |
Closed |
|
Bank accepts an agreed amount under a compromise arrangement |
Full outstanding dues are paid |
|
May be reported as settled |
May be reported as closed |
|
Can negatively affect creditworthiness |
Generally more favourable for future borrowing |
|
May influence future credit applications |
Future approval still depends on overall credit profile |
Borrowers should understand this distinction before accepting an OTS offer.
Does PNB Credit Card Settlement Affect Your CIBIL Score?
Yes. A PNB credit card account settled for less than the full outstanding amount can negatively affect your credit profile.
When the account is reported as "Settled", future lenders may interpret it as an indication that the original repayment obligation was not paid in full.
This can influence future applications for:
- Personal loans.
- Home loans.
- Vehicle loans.
- New credit cards.
- Other credit facilities.
The actual impact depends on your complete credit history and the lender's assessment.
Can PNB Change a Settled Status to Closed?
PNB's published policy acknowledges requests from cardholders seeking a change from settled status to normal closure.
It also refers to separate operational guidelines for dealing with such requests.
However, borrowers should not assume that paying the agreed settlement amount automatically changes the credit-report status.
If you have completed an OTS and want to understand whether a status correction or other update is possible, contact PNB through official channels and ask about the applicable policy.
Any change depends on the bank's requirements and approval.
How Can You Rebuild Your Credit Profile After Settlement?
After completing settlement, responsible financial behaviour can help you work towards better credit health.
Consider the following steps:
- Obtain and preserve your settlement confirmation.
- Review your credit report regularly.
- Check that the settled account is reported accurately.
- Raise a dispute if incorrect information appears.
- Pay other active credit obligations on time.
- Avoid unnecessary borrowing.
- Maintain manageable credit utilisation.
There is no guaranteed credit-score recovery timeline.
What Are the Alternatives to PNB Credit Card Settlement?
Settlement is not necessarily the best option for every borrower.
Before considering OTS, evaluate whether another repayment arrangement may be more suitable.
1. PNB Balance EMI Facility
PNB's published Credit Card Business Policy mentions a Balance EMI facility through which eligible outstanding credit card dues can be converted into instalments, subject to applicable conditions.
This may help borrowers who can repay the outstanding amount over time but need a more manageable payment structure.
Review the interest, fees and repayment schedule before accepting.
2. PNB Easy Pay Plan
The bank's policy also describes EMI facilities for eligible purchases and transactions.
The availability and conditions depend on the specific card facility and applicable terms.
3. Balance Transfer Facility
PNB's policy describes a balance transfer facility for transferring an eligible outstanding credit card balance from another bank to a PNB credit card under an EMI arrangement.
This is subject to eligibility and applicable conditions.
Borrowers should compare the total borrowing cost before using balance transfer as a debt-management strategy.
4. Structured Repayment
If your financial problem is temporary, a repayment budget may help you resume regular payments.
Contact the bank and understand whether any repayment arrangement is available for your account.
5. Debt Consolidation
If you have multiple outstanding loans and credit card dues, debt consolidation may be worth evaluating.
However, taking a new loan is not automatically beneficial. Compare the interest rate, processing fees, tenure and total repayment amount.
6. Compromise Settlement
If you are facing serious financial hardship and full repayment is genuinely not possible, you may request consideration of a compromise settlement.
The bank independently decides whether to approve it and determines the applicable terms.
Can PNB Recovery Agents Harass Credit Cardholders?
Borrowers should know that recovery activities must comply with applicable RBI instructions.
RBI has issued directions requiring credit card issuers and their recovery agents to follow appropriate recovery practices and maintain customer confidentiality.
Recovery agents must not engage in intimidation, harassment or inappropriate communication.
Borrowers should be aware of restrictions involving:
- Threatening or anonymous calls.
- Verbal or physical intimidation.
- Public humiliation.
- Intrusion into the privacy of family members or friends.
- Inappropriate messages.
- Persistent calls intended to harass.
- Recovery calls before 8:00 a.m. or after 7:00 p.m. under applicable RBI instructions.
If you experience inappropriate recovery practices, preserve relevant call records, messages and other evidence.
You can raise a complaint through PNB's official grievance-redressal channels. If the issue remains unresolved after following the applicable process, you may explore the RBI complaint-redressal mechanism, subject to its eligibility requirements.
Remember that concerns about recovery practices do not automatically cancel legitimate outstanding dues.
Important Precautions Before PNB Credit Card OTS
Before accepting a settlement offer, keep these points in mind.
Do not rely on verbal promises: Obtain written confirmation of the approved amount and terms.
Verify the communication: PNB's credit-card business involves its subsidiary, PNB Cards & Services Ltd. Verify the identity and authority of anyone contacting you.
Do not pay personal accounts: Use only verified payment channels.
Understand CIBIL implications: A settled account may affect future borrowing opportunities.
Check the payment deadline: Follow the schedule in the approved OTS letter.
Preserve documents: Keep settlement letters, receipts and final confirmation.
Avoid guaranteed settlement claims: No third party can independently guarantee PNB's approval or a particular settlement amount.
How ReducedDebts Helps Borrowers With PNB Credit Card Debt
Managing credit card dues can become difficult when outstanding balances, multiple EMIs and household expenses start overlapping.
ReducedDebts is a debt resolution and loan settlement platform in India helping individuals and businesses understand their financial challenges and explore suitable debt-resolution options.
For borrowers dealing with PNB credit card dues or other outstanding debts, guidance may include:
- Understanding the overall debt position.
- Reviewing repayment difficulties.
- Exploring available debt-resolution options.
- Understanding settlement and its potential consequences.
- Preparing for discussions with lenders.
- Understanding credit-report implications.
- Reviewing documentation and payment precautions.
Our approach focuses on transparent assessment, realistic expectations and informed financial decisions.
Every borrower's situation is different. Any OTS or settlement arrangement remains subject to PNB's applicable policies, terms and approval.
If you are struggling with PNB credit card dues, visit ReducedDebts to understand your debt-resolution options.
Final Thoughts
PNB credit card settlement can be a possible resolution option for borrowers facing serious repayment difficulties.
PNB's published policy confirms that the bank has an OTS framework for NPA credit card accounts and that accounts closed under OTS are reported as settled to credit information companies.
However, settlement should not be considered an automatic right or a guaranteed way to reduce debt.
Before proceeding, understand your outstanding dues, review available repayment alternatives, verify the written offer and consider the potential impact on your credit profile.
A well-informed decision can help you approach financial difficulties with greater clarity and avoid unnecessary financial risks.
Need help understanding your credit card debt? Connect with ReducedDebts to explore your available debt-resolution options.
Disclaimer: This article is for general educational and informational purposes only and does not constitute financial or legal advice. ReducedDebts is not a lender or a law firm and is not affiliated with Punjab National Bank. PNB independently determines settlement eligibility, amounts and conditions under its applicable policies. No settlement amount, debt reduction or credit-score improvement is guaranteed. Always verify account-specific information directly with PNB before making financial decisions.