What Is Kotak Loan Settlement?
Kotak loan settlement is a negotiated arrangement in which Kotak Mahindra Bank may agree to accept an amount lower than the total outstanding dues to resolve a borrower's account.
This is commonly referred to as a compromise settlement or One-Time Settlement (OTS).
For example, imagine a borrower has an outstanding personal loan balance that has become difficult to repay because of a significant loss of income. The borrower approaches the bank and requests a resolution based on their financial circumstances.
After evaluating the account and applicable policies, the bank may consider accepting an agreed amount to resolve the outstanding claim.
The amount, payment conditions and settlement approval are determined by the bank.
Important: Loan settlement is not an automatic right of the borrower. RBI guidelines recognise compromise settlements as a resolution mechanism, but the decision rests with the bank under its approved policy and commercial judgement.
Can You Settle a Loan With Kotak Mahindra Bank?
A borrower facing genuine financial hardship can approach Kotak Mahindra Bank to discuss possible repayment or resolution options, including a compromise settlement where applicable.
However, approval depends on the account, the borrower's circumstances and the bank's internal policy.
The bank may consider factors such as:
- Outstanding loan amount.
- Repayment history.
- Duration and nature of overdue payments.
- Current financial condition.
- Income reduction or employment loss.
- Medical or other exceptional expenses.
- Ability to arrange repayment.
- Applicable bank policies and regulatory requirements.
A borrower should not assume that missing a certain number of EMIs automatically qualifies the account for settlement.
It is important to communicate with the bank and understand the available options before making a decision.
Which Kotak Loans Can Be Considered for Settlement?
Borrowers may have different types of credit facilities with Kotak Mahindra Bank. The available resolution options depend on the specific product, security and account circumstances.
1. Kotak Personal Loan Settlement
Personal loans are generally unsecured credit facilities. Borrowers who experience serious repayment difficulties may approach the bank to discuss available resolution options.
A compromise settlement may be considered by the bank, subject to its policies and approval.
2. Kotak Credit Card Settlement
Credit card dues can increase when outstanding balances remain unpaid and applicable interest and charges accumulate.
Borrowers facing difficulties managing Kotak credit card dues can contact the bank to discuss repayment options and whether a compromise settlement may be considered.
3. Kotak Business Loan Settlement
Business borrowers experiencing financial stress may also need to explore resolution options for their outstanding business obligations.
The available arrangements depend on the type of facility, security, borrower structure and applicable banking policies.
4. Secured Loan Accounts
Home loans, vehicle loans and other secured facilities involve collateral or financed assets.
These accounts have different contractual and recovery considerations. A borrower should not assume that the same settlement process used for an unsecured personal loan will apply to a secured loan.
The bank's willingness to consider a compromise arrangement depends on the specific facility and applicable policy.
When Does Kotak Mahindra Bank Consider Loan Settlement?
There is no single universal condition that guarantees settlement approval.
A bank may examine a borrower's financial circumstances, account status, repayment history and recovery prospects before considering a compromise settlement.
Common circumstances that may lead borrowers to request assistance include:
- Job loss or sudden unemployment.
- Business losses or closure.
- Reduced monthly income.
- Major medical expenses.
- Family emergencies.
- Multiple outstanding loans.
- Long-term repayment difficulties.
Does the Loan Need to Become an NPA Before Settlement?
An important point to understand is the difference between NPA classification and settlement eligibility.
Under applicable RBI income-recognition and asset-classification norms, a term loan account is generally classified as a non-performing asset when principal or interest remains overdue for more than 90 days.
However, borrowers should not treat the 90-day period as an automatic settlement eligibility rule.
NPA classification and compromise settlement are separate regulatory and banking concepts. The bank evaluates settlement requests under its approved policy and applicable regulations.
Borrowers should avoid deliberately missing EMIs simply to try to qualify for settlement.
Kotak Loan Settlement Percentage: How Much Can the Bank Accept?
There is no fixed or publicly guaranteed Kotak loan settlement percentage applicable to every borrower.
The settlement amount, if approved, depends on the bank's evaluation of the individual account.
Several factors may influence the decision:
Outstanding balance: The bank considers the total amount due under the loan or credit facility.
Financial hardship: The borrower's current income, expenses and supporting documents may be considered.
Repayment history: Previous repayments and the account's current status may form part of the assessment.
Security and collateral: Secured facilities require different considerations from unsecured loans.
Recovery prospects: The bank may assess the amount it can reasonably recover through different resolution options.
Bank policy: The final settlement amount and terms are subject to the bank's approved policies and authorised approval process.
Should You Trust Guaranteed Kotak Settlement Percentage Offers?
Be careful when an agent or third-party website promises a specific percentage of loan reduction.
Another borrower's settlement outcome does not establish what Kotak Mahindra Bank will offer in your case.
Do not make payments based on verbal promises or unofficial calculations. Obtain and verify the bank's written settlement terms before proceeding.
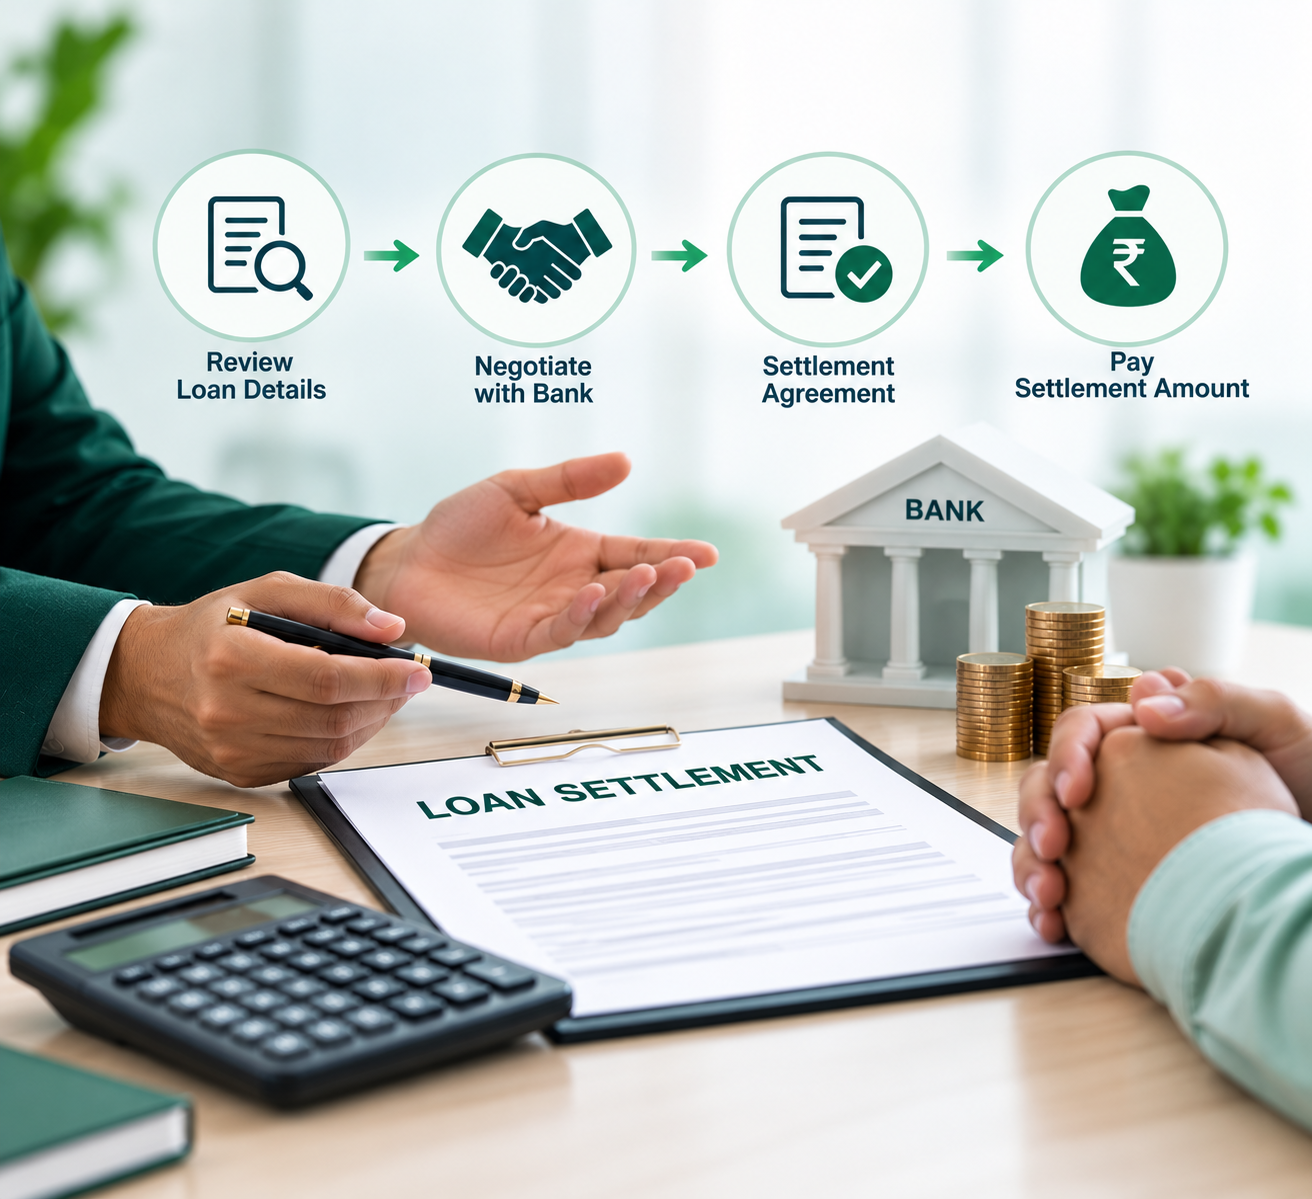
Kotak Loan Settlement Process: Step-by-Step
If you are struggling with Kotak loan repayments, follow a structured approach to understand your options.
Step 1: Check Your Loan Outstanding
Start by reviewing your latest Kotak loan statement.
Identify:
- Total outstanding balance.
- Principal outstanding.
- Applicable interest and charges.
- Overdue instalments.
- Previous repayment records.
- Any notices or communication received from the bank.
This helps establish the current position of your loan account.
Step 2: Assess Your Financial Situation
Prepare a realistic picture of your income and expenses.
Consider your monthly salary or business income, household expenses, other loan EMIs, credit card dues and any exceptional financial commitments.
Determine how much you can realistically pay without creating further financial difficulties.
Step 3: Contact Kotak Mahindra Bank
Use the bank's official customer-service or grievance channels to explain your repayment difficulties.
Ask about the options available for your account.
Depending on your circumstances, these may include:
- Regular repayment.
- Eligible EMI or repayment arrangements.
- Restructuring, where available.
- Other repayment solutions.
- Compromise settlement, if the bank is willing to consider it.
Keep copies of your communication.
Step 4: Explain Your Financial Hardship
If you are requesting a settlement consideration, explain why you cannot repay the full amount under the existing arrangement.
Be clear and factual.
For example, explain whether your financial difficulties resulted from employment loss, business disruption, medical expenses or another significant change.
Provide genuine supporting documents if requested.
Step 5: Review the Bank's Written Offer
If the bank approves a compromise settlement, obtain the complete written offer.
Review the following:
- Settlement amount.
- Payment deadline.
- Instalment conditions, if applicable.
- Account details and payment instructions.
- Conditions for completing the settlement.
- Consequences of missing the agreed payment.
- Credit-reporting implications.
- Treatment of any remaining claim, as stated in the agreement.
Do not rely solely on an oral assurance from a recovery representative.
Step 6: Make Payment Through Verified Bank Channels
Once you have verified the settlement terms, follow the payment instructions stated in the bank's official communication.
Never transfer money to a personal UPI ID, QR code or individual bank account on the promise that someone will arrange a settlement.
Retain the transaction reference and payment receipt.
Step 7: Obtain Written Settlement Confirmation
After completing the agreed payment, request written confirmation from Kotak Mahindra Bank.
Keep the settlement letter, payment proof and subsequent account communication.
Check your credit report later to verify that the account information has been reported accurately.
What Documents May Be Required for Kotak Loan Settlement?
The documents required can vary depending on the loan type, account status and the bank's assessment.
You may be asked to provide:
Identity and Loan Documents
- PAN card or other accepted identity proof.
- Loan account details.
- Latest loan statement.
- Previous repayment records.
- Relevant bank communication.
Financial Hardship Documents
- Recent salary slips.
- Bank statements.
- Employment termination or job-loss letter.
- Medical bills, where applicable.
- Business income or loss records.
- Business closure documents, where relevant.
- Other evidence explaining the financial difficulty.
Submitting accurate documents helps the bank understand your circumstances.
Do not submit false documents or make misleading claims about your financial position.
Does Kotak Loan Settlement Affect Your CIBIL Score?
Yes. Loan settlement can negatively affect your credit profile.
When a bank accepts an amount lower than the full outstanding dues, the account may be reported as "Settled" to credit information companies.
This is different from an account reported as "Closed" after full repayment.
Settled vs Closed: What Is the Difference?
|
Settled |
Closed |
|
Bank accepts an agreed amount lower than the total outstanding dues |
Full outstanding dues are paid |
|
Account may carry a settled status |
Account may carry a closed status |
|
Can negatively affect creditworthiness |
Generally more favourable than settled status |
|
May affect future credit applications |
Future approval still depends on overall credit profile |
How Does a Settled Account Affect Future Loans?
Banks and financial institutions review credit reports when evaluating loan or credit card applications.
A settled account may indicate that the borrower did not repay the entire contractual outstanding amount.
As a result, future lenders may consider the account status when evaluating a new application.
The actual decision depends on the lender's credit policy, income assessment and complete credit history.
Can You Improve Your CIBIL Score After Kotak Loan Settlement?
Credit health can be rebuilt over time through responsible financial behaviour.
Some practical steps include:
- Obtain and preserve the settlement confirmation.
- Review your credit report regularly.
- Check that the reported account status is accurate.
- Raise a dispute if incorrect information appears.
- Pay other active credit obligations on time.
- Avoid unnecessary borrowing and repeated credit applications.
- Maintain manageable credit utilisation.
If you later pay an amount that was previously unpaid, contact the bank to understand whether the account status can be updated. Any correction depends on the lender's confirmation and applicable reporting rules.
There is no guaranteed credit-score recovery period.
What Happens If You Cannot Pay Your Kotak Loan EMI?
If you miss a loan EMI, the bank may take steps according to the loan agreement and applicable regulations.
Possible consequences include:
- Late payment charges or applicable penalties.
- Additional interest as per the agreement.
- Follow-up communication from the bank.
- Reporting of overdue information to credit bureaus.
- Account classification under applicable prudential norms.
- Recovery action in accordance with the agreement and law.
If you are unable to pay your EMI, do not ignore the situation.
Contact the bank, understand the amount due and ask about the available repayment options.
Early communication may help you understand the possible solutions before the outstanding amount becomes more difficult to manage.
Can Kotak Bank Recovery Agents Harass Borrowers?
Recovery of outstanding dues must follow applicable RBI instructions and other relevant laws.
RBI guidelines prohibit regulated entities and their recovery agents from using intimidation or harassment during recovery activities.
Borrowers should be aware of restrictions involving:
- Threatening or anonymous calls.
- Verbal or physical intimidation.
- Public humiliation.
- Inappropriate messages.
- Intrusion into the privacy of family members or friends.
- Persistent calls intended to harass.
- Recovery calls before 8:00 a.m. or after 7:00 p.m. under applicable RBI instructions.
If you experience inappropriate recovery practices, maintain records of calls, messages and other communications.
You may raise a complaint through Kotak's official grievance-redressal channels. If the complaint remains unresolved after following the applicable process, you may consider the RBI's complaint-redressal mechanism, subject to its eligibility requirements.
Borrowers should remember that concerns about recovery conduct do not automatically cancel legitimate loan obligations.
Alternatives to Kotak Loan Settlement
Settlement may not be the most suitable option for every borrower.
Before choosing it, consider whether another repayment arrangement could address your financial difficulty.
1. Loan Restructuring
Where available and approved by the bank, restructuring may change certain repayment terms to make the loan more manageable.
The revised terms may involve changes to repayment schedules or other conditions.
Ask the bank about eligibility, additional costs and the long-term financial impact.
2. EMI Conversion or Repayment Adjustment
For eligible credit facilities, the bank may offer specific instalment or repayment arrangements.
Understand the applicable interest, charges and total amount payable before accepting.
3. Debt Consolidation
If you have multiple loans and credit card balances, debt consolidation may help combine eligible obligations into a single repayment facility.
However, taking another loan is not automatically beneficial. Compare the total borrowing cost, fees, tenure and repayment capacity.
4. Full Repayment Through Financial Planning
If your financial difficulty is temporary, a structured monthly budget may help you resume regular repayments.
Prioritise essential expenses and review unnecessary spending while keeping your lenders informed.
5. Professional Debt-Resolution Guidance
If multiple outstanding loans have become difficult to manage, professional guidance may help you understand your financial position and evaluate possible resolution options.
The appropriate solution depends on your circumstances and the lender's approval.
Common Mistakes to Avoid During Kotak Loan Settlement
Before proceeding with any settlement request, avoid these common mistakes.
Assuming settlement is guaranteed: A bank independently decides whether to approve a compromise settlement.
Believing that 90 days automatically qualifies you: NPA classification does not create an automatic right to settlement.
Trusting fixed settlement percentages: Settlement amounts vary according to the account and bank assessment.
Paying without a written offer: Verify the bank's official settlement terms before transferring money.
Ignoring CIBIL consequences: A settled account may affect future credit applications.
Making payments to personal accounts: Use only verified bank payment channels.
Ignoring other repayment options: Consider whether restructuring or a manageable repayment plan may be more suitable.
How ReducedDebts Helps Borrowers With Kotak Loan Repayment Difficulties
When loan repayments become difficult, borrowers often need clarity about their outstanding obligations, repayment capacity and available debt-resolution options.
ReducedDebts is a debt resolution and loan settlement platform in India helping individuals and businesses navigate financial difficulties related to personal loans, credit card dues, multiple EMIs and other outstanding obligations.
For borrowers dealing with Kotak loan repayment difficulties, guidance may include:
- Understanding the overall debt position.
- Reviewing repayment challenges.
- Exploring suitable debt-resolution options.
- Understanding the potential implications of loan settlement.
- Preparing for lender discussions.
- Understanding documentation and payment precautions.
- Reviewing concerns related to credit-report status.
Our approach focuses on transparent assessment and informed decision-making rather than guaranteed settlement or credit-score promises.
Every financial situation is different. Any settlement or repayment arrangement remains subject to the respective lender's policies, terms and approval.
If you are struggling with Kotak loan EMIs or multiple outstanding debts, visit ReducedDebts to understand your available debt-resolution options.
Final Thoughts
Kotak loan settlement may be one possible resolution option for borrowers facing serious repayment difficulties. However, it should not be treated as an automatic or guaranteed way to reduce outstanding debt.
Before choosing settlement, understand your financial position, review alternative repayment arrangements and consider the potential effect on your credit history.
Always verify settlement terms directly with Kotak Mahindra Bank, make payments through official channels and preserve all relevant documents.
A well-informed financial decision can help you approach debt-related challenges more responsibly and plan your next steps with greater clarity.
Need help understanding your loan repayment difficulties? Connect with ReducedDebts to explore your debt-resolution options.
Disclaimer: This article is for general educational and informational purposes only and does not constitute financial or legal advice. ReducedDebts is not a lender or a law firm. Kotak Mahindra Bank independently determines whether to approve a compromise settlement and the terms of any arrangement. No settlement amount, debt reduction or credit-score improvement is guaranteed. Borrowers should verify account-specific information directly with the bank and review applicable loan terms before making financial decisions.