Quick Answer: How Can I Check If a Debt Settlement Company Is Genuine?
Before hiring a debt settlement company, check these areas:
- Verify the company's legal identity and contact information.
- Check whether its website clearly explains its services.
- Understand whether it is a lender, debt-resolution service provider, consultant or another type of business.
- Ask exactly how the company works with lenders.
- Demand a written agreement before paying.
- Understand every fee and additional charge.
- Never accept guaranteed settlement or CIBIL promises.
- Verify every payment channel independently.
- Ask how your personal and financial information will be protected.
- Check independent reviews and look for patterns—not just star ratings.
- Ask what happens if the lender rejects the proposal.
- Understand the potential credit consequences of settlement.
- Do not allow anyone to misrepresent itself as your bank, NBFC or government authority.
- Avoid companies that pressure you into immediate payment.
- Compare more than one provider before making a decision.
A genuine company should be willing to explain its process clearly rather than relying on pressure, fear or unrealistic promises.
What Does a Debt Settlement Company Actually Do?
The first thing to understand is that a debt settlement company is not necessarily the lender.
A lender is the institution that originally provided the credit or currently owns/serves the debt.
A debt-resolution or settlement company may instead provide services such as:
- Financial assessment
- Debt counselling
- Debt-resolution planning
- Communication support
- Negotiation assistance
- Settlement proposal assistance
- Documentation support
- Multi-debt assessment
- Repayment planning
The exact services vary by company.
The lender remains the party that determines whether it will accept a settlement proposal and on what terms.
This distinction is extremely important.
A company can help you present and manage a settlement process.
It cannot simply declare that your lender must accept a particular amount.
Is a Debt Settlement Company the Same as a Bank or NBFC?
No.
A debt settlement company should not be confused with:
- Bank
- NBFC
- Credit card issuer
- Loan provider
- Credit bureau
- Government authority
A borrower should know exactly who they are dealing with.
If a company presents itself as a lender, asks for loan-related payments or makes claims about being officially connected with a bank, verify those claims independently.
This is especially important because CIBIL has itself warned consumers that certain entities make false claims about partnering with TransUnion CIBIL. CIBIL advises consumers to verify official partners through its published information rather than relying on a company's own claim.
Step 1: Verify the Company's Identity
Start with the basics.
Look for:
- Legal business name
- Registered office address
- Website
- Business email
- Telephone number
- Customer-support details
- Terms and conditions
- Privacy policy
- Refund/cancellation policy, where applicable
- Company identification details where provided
A professional company should not make its identity unnecessarily difficult to verify.
Be cautious if:
- The website has no physical address
- Only a mobile number is provided
- You cannot find terms and conditions
- There is no privacy policy
- The company refuses to identify the legal entity
- You are asked to communicate only through an individual's WhatsApp number
- The person refuses to provide written documentation
A polished website alone does not prove that a company is genuine.
The goal is to establish:
Who is actually providing the service?
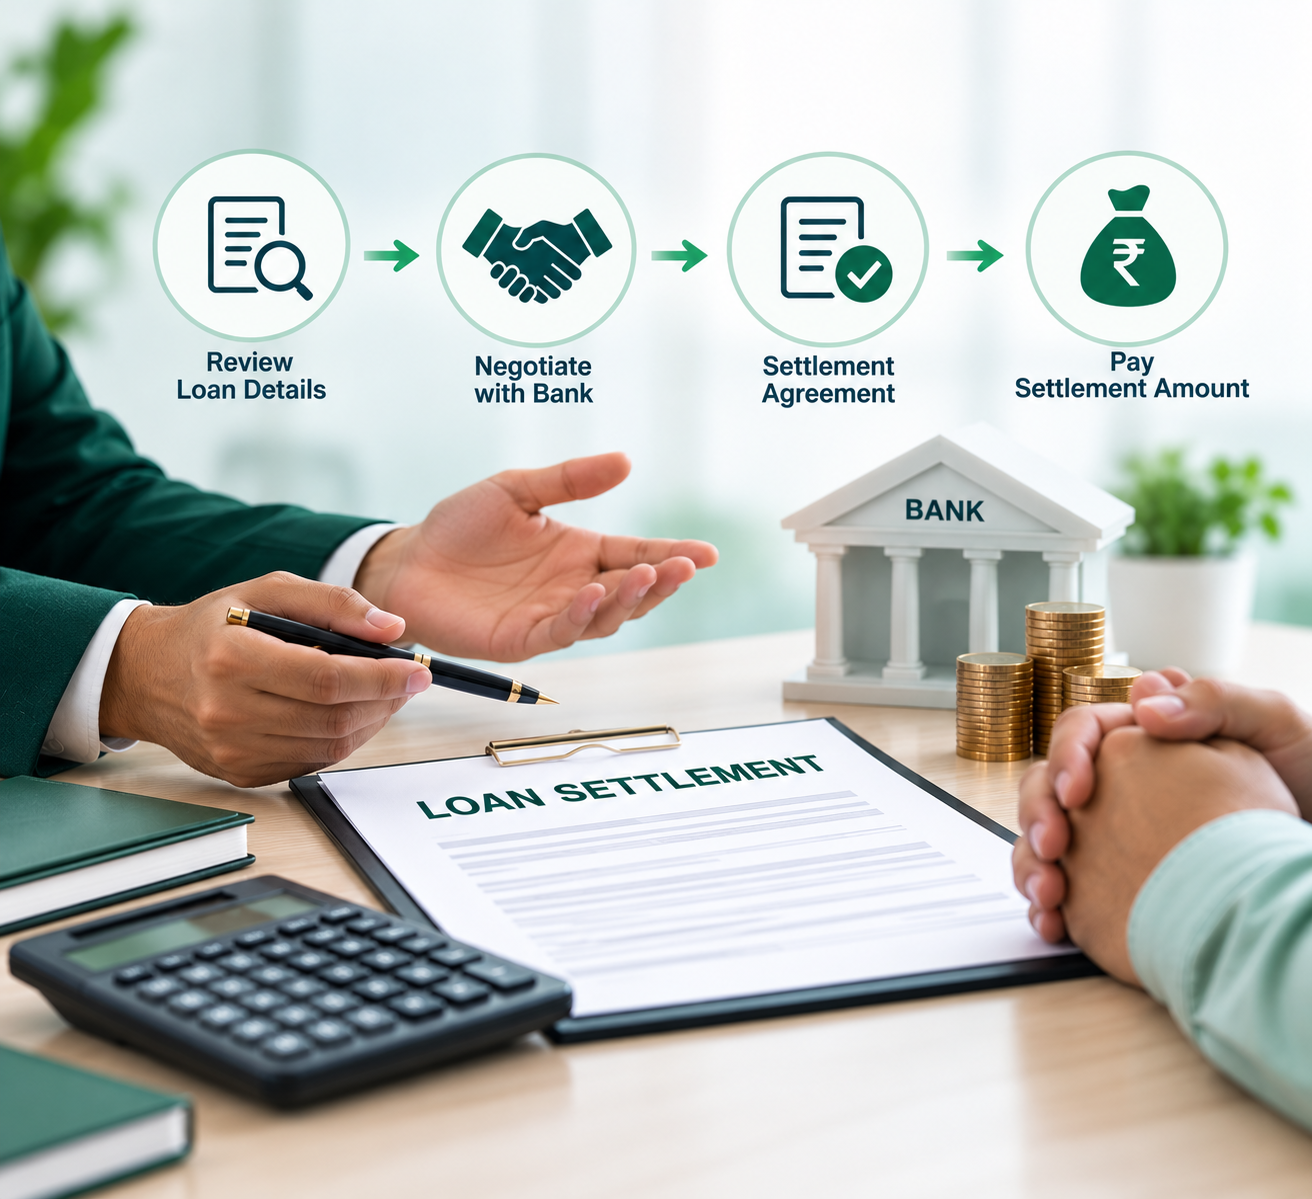
Step 2: Check Whether the Website Explains the Process
A genuine debt-resolution company should be able to explain its process.
Look for information about:
Assessment
How does the company understand your debt situation?
Documentation
What documents will it need?
Lender communication
How will it communicate with lenders?
Negotiation
Who negotiates and how?
Settlement
What happens if the lender agrees?
Rejection
What happens if the lender does not agree?
Payments
How are settlement payments made?
Fees
When and how does the company charge its service fees?
If the entire business model is simply:
“Pay us ₹X and we will reduce your loan by ₹Y.”
you should ask many more questions before proceeding.
Step 3: Ask the Most Important Question — Who Decides the Settlement Amount?
This is perhaps the most important test.
Ask:
“Can you guarantee that my lender will accept the settlement amount you propose?”
A responsible company should explain that the lender's acceptance is not something the company can guarantee.
A settlement generally involves an agreement between the borrower and the lender.
The company's role may be to assist with the process, depending on its service model.
But the borrower should understand:
Debt settlement is not the same as purchasing a product with a fixed price.
The final terms depend on the relevant lender and the circumstances of the account.
Step 4: Be Extremely Careful With Guaranteed Settlement Claims
One of the biggest warning signs is an absolute guarantee.
Be cautious of statements such as:
- “Guaranteed 70% settlement”
- “Guaranteed 80% waiver”
- “Every loan will be settled”
- “Bank has already approved your settlement”
- “Settlement is guaranteed”
- “Your loan will definitely be closed”
- “We can remove your entire debt”
- “No negotiation is required”
The problem is simple:
The settlement decision is not entirely controlled by the service provider.
A company may have experience handling debt-resolution cases.
That does not mean it can guarantee what a lender will accept.
A more credible company should explain the factors that can influence settlement discussions, such as:
- Outstanding amount
- Loan type
- Account status
- Repayment history
- Financial hardship
- Lender policy
- Available repayment capacity
- Documentation
- Negotiation circumstances
Step 5: Be Suspicious of Guaranteed CIBIL Improvement
Another major red flag is:
“We guarantee that your CIBIL score will increase after settlement.”
A company cannot responsibly promise a specific future credit-score outcome.
More importantly, settlement itself can have negative implications for a borrower's credit profile.
CIBIL explains that when a borrower pays an amount lower than the total outstanding with the lender's consent, the account can be reported as “settled.” CIBIL also states that settled accounts are not viewed favourably by lenders.
Therefore, a company that tells you:
“Settlement will improve your CIBIL immediately.”
should be treated cautiously.
A responsible provider should explain both:
Potential debt-resolution benefits
and
Potential credit consequences.
What Is the Difference Between “Settled” and “Closed”?
This is extremely important before choosing a settlement service.
Closed
Generally means the borrower has fulfilled the contractual repayment obligation and the account has been closed.
Settled
CIBIL explains that a settled status can reflect a situation where the borrower has made a partial payment, with the lender's consent, against the total outstanding.
CIBIL's consumer guidance specifically notes that settled accounts are not viewed favourably by lenders.
Therefore, if a company tells you:
“Settlement is exactly the same as normal loan closure.”
ask for clarification.
They are not necessarily equivalent from a credit-reporting perspective.
Step 6: Ask for a Written Fee Structure
Before signing up, ask:
What is your service fee?
Is GST included?
Is the fee one-time or recurring?
Is there a success fee?
Are there documentation charges?
Are there additional negotiation charges?
Are there cancellation or refund conditions?
What happens if the lender rejects the settlement?
What happens if I discontinue the service?
Get the answers in writing.
Do not rely solely on:
“Sir/Madam, don't worry. Everything is included.”
Financial arrangements should be documented.
Why Transparent Fees Matter
Suppose a company tells you:
“We charge 10%.”
Ask:
10% of what?
It could potentially mean:
- Total outstanding
- Settlement amount
- Amount saved
- Monthly instalment
- Another defined calculation
The basis should be explicitly stated in the agreement.
For example:
Service Fee = X% of [clearly defined amount] + applicable taxes
A borrower should not have to guess how the fee is calculated.
Step 7: Never Pay Into an Unverified Personal Account
This is one of the most important practical checks.
Be extremely cautious if someone asks you to transfer money to:
- Personal UPI
- Employee's personal bank account
- Individual wallet
- Unrelated company
- Unknown QR code
- Cash without documentation
Before making a payment, verify:
Who is receiving the money?
Why are they receiving it?
What does the agreement say?
What document or invoice supports the payment?
For settlement payments specifically, borrowers should understand whether money is being paid toward:
the lender's settlement obligation
or
the service provider's fee.
Do not confuse the two.
Step 8: Understand Where Settlement Money Actually Goes
Suppose a lender agrees to settle an account for:
₹2,00,000
A borrower should know:
- Who must receive the ₹2,00,000?
- Is there a formal settlement letter?
- What is the payment deadline?
- Is the amount paid directly to the lender?
- What receipt will be issued?
- What happens after the payment?
- What documentation confirms completion?
The borrower should not rely on a verbal statement such as:
“Just transfer the money to us. We will handle everything.”
Always understand the payment trail.
Step 9: Ask for the Settlement Letter
Never rely solely on a phone conversation saying:
“Your settlement has been approved.”
Ask for written confirmation from the relevant lender or an appropriate official document showing the agreed terms.
The document should be carefully reviewed for:
- Loan/account number
- Settlement amount
- Payment schedule
- Payment deadline
- Conditions
- Consequences of non-payment
- Closure/settlement status
- Other relevant terms
If the amount is significant, consider getting independent professional advice before making the final payment.
Step 10: Verify Lender Communication Independently
Suppose a debt-resolution company tells you:
“The bank has approved ₹1.5 lakh.”
Do not rely solely on the company's statement.
Where possible, verify the information with the lender through an official channel.
Use:
- Official customer-care number
- Official email
- Bank branch
- Official lender website
- Secure lender app/portal
Do not use a phone number supplied only by an unknown intermediary when independently verifying a settlement.
Step 11: Ask What Happens If the Lender Says No
This question separates a transparent company from a sales-driven one.
Ask:
“What happens if my lender does not agree to the proposed settlement?”
A responsible company should explain the possible next steps.
Those may include:
- Reassessing the proposal
- Continuing negotiations
- Considering restructuring
- Exploring repayment options
- Reviewing consolidation
- Reassessing affordability
- Ending the engagement according to the contract
There should be no mystery.
Step 12: Check Whether the Company Explains Alternatives
A genuine debt-resolution approach should not automatically push every borrower toward settlement.
Depending on the circumstances, alternatives may include:
Regular repayment
If the borrower can still afford the EMI, continuing normal repayment may be preferable.
Restructuring
A lender may offer changes to repayment terms in appropriate cases.
Tenure extension
A longer tenure may reduce monthly EMI but increase total interest.
Consolidation
Multiple debts may potentially be combined into one arrangement if suitable.
Refinancing
A borrower may investigate whether another lender can provide better terms.
Part-prepayment
A reduction in principal may reduce future interest depending on the loan structure.
Settlement
Settlement may be considered where genuine financial hardship makes regular repayment impractical and the lender is willing to agree.
If a company tells every borrower:
“Settlement is the only solution.”
ask why.
Step 13: Ask About Your Credit Report Before You Sign
A professional discussion should include the potential effect on your credit profile.
Ask:
- How will the account potentially be reported?
- Will it show as settled or closed?
- What happens to overdue information?
- Who updates the credit bureau?
- What documentation will I receive?
- What happens if the credit report is not updated correctly?
CIBIL explains that credit-report information is supplied by credit institutions and that inaccuracies require the relevant information to be corrected through the applicable dispute process.
This means a debt-resolution company should not tell you:
“We can directly change your CIBIL record.”
Be cautious of anyone making that claim.
Can a Debt Settlement Company Remove a Default From CIBIL?
A company should not promise that it can simply delete legitimate negative information from your credit report.
Credit information is reported by credit institutions.
CIBIL explains that account status and repayment information form part of the credit report, and disputes over inaccurate information follow a verification process involving the relevant credit institution.
So be very cautious if someone promises:
- “We will delete your default.”
- “We will remove your settled status.”
- “We will increase your CIBIL score by 200 points.”
- “We have a direct CIBIL connection.”
- “CIBIL will be changed within 24 hours.”
A genuine company should explain the process rather than selling certainty.
Step 14: Protect Your Personal and Financial Documents
Debt-resolution companies may need access to sensitive information to understand your financial position.
This can include:
- PAN
- Identity documents
- Loan sta