Quick Answer: How Can You Celebrate Diwali Without Increasing Debt?
The simplest approach is to decide your Diwali budget before you start shopping and spend only what you can realistically afford from your current income or available savings.
A practical Diwali financial plan should:
- Set a total festive spending limit.
- Separate essential and optional expenses.
- Protect money required for regular EMIs and household expenses.
- Avoid taking a new loan simply for festival consumption.
- Avoid unnecessary credit-card purchases that cannot be repaid.
- Compare prices before making large purchases.
- Keep an emergency fund untouched where possible.
- Track expenses throughout the festive period.
- Plan how any credit-card balance will be repaid.
- Avoid borrowing from one source to pay another debt.
The Reserve Bank of India’s financial-awareness guidance specifically encourages responsible borrowing and cautions against borrowing for consumption expenses such as celebrating festivals when those expenses can instead be met through current income or savings.
Why Can Diwali Spending Become a Debt Problem?
Diwali expenses often arrive together.
You may have:
- New clothes
- Gifts
- Sweets and dry fruits
- Home decoration
- Travel expenses
- Electronics
- Jewellery
- Festival events
- Family functions
- Dining and entertainment
- Additional household purchases
Individually, these expenses may not appear significant. But when several purchases are made within a few weeks, the total can become much larger than expected.
For example, consider a household that already has monthly EMIs of ₹35,000.
During Diwali, it spends:
- ₹8,000 on clothes
- ₹7,000 on gifts
- ₹5,000 on decoration
- ₹10,000 on travel
- ₹15,000 on shopping and celebrations
The additional festive expenditure becomes ₹45,000.
If the household does not have enough savings to cover this amount, it may put a large portion of the spending on a credit card or borrow additional money.
The celebration may last a few days, but the repayment obligation can continue for months.
That is where festive debt can become a financial burden.
What Is Festive Debt?
Festive debt is debt created or increased because of spending associated with festivals and celebrations.
It is not a separate official loan category. Instead, the term describes a situation where someone uses borrowed money or credit to fund festival-related expenses and later struggles to repay it.
Festive debt may come from:
- Credit-card purchases
- Personal loans
- Consumer loans
- Buy Now Pay Later facilities
- Borrowing from friends or family
- Loan apps
- Other forms of short-term borrowing
The concern becomes greater when a person already has significant financial obligations.
For example:
Existing EMI + new personal loan + credit-card balance + festive expenses = increased monthly financial pressure.
This is why Diwali financial planning should begin before shopping rather than after the bills arrive.
How Much Should You Spend on Diwali?
There is no single Diwali spending limit that works for every household.
Your budget should depend on:
- Monthly income
- Existing EMIs
- Household expenses
- Savings
- Emergency fund
- Existing credit-card balance
- Upcoming financial commitments
- Number of dependants
- Expected income for the coming months
A useful starting point is to calculate your available festive budget, rather than deciding what you want to buy first.
Simple calculation
Monthly income – essential expenses – existing debt payments – necessary savings = amount potentially available for discretionary spending
The resulting amount should not automatically become your Diwali shopping budget.
You should also consider upcoming expenses and unexpected financial needs.
If your finances are already tight, a smaller celebration may be financially healthier than borrowing money for a larger one.
7 Practical Ways to Control Diwali Spending
1. Create a Diwali Budget Before Shopping
Do not begin with a shopping list alone.
Start with a total spending limit.
For example:
|
Category |
Planned Budget |
|
Gifts |
₹8,000 |
|
Clothes |
₹6,000 |
|
Home decoration |
₹3,000 |
|
Sweets |
₹3,000 |
|
Travel |
₹5,000 |
|
Family celebration |
₹3,000 |
|
Total |
₹28,000 |
The actual numbers will differ from household to household.
The important point is to establish a limit before spending begins.
2. Separate Needs From Wants
Festive advertising can make many purchases feel urgent.
Before buying something, ask:
Do I need this, or do I simply want it because it is on a festive offer?
For example:
More essential
- Necessary travel
- Basic clothing
- Gifts within your planned budget
- Household requirements
Potentially discretionary
- Expensive gadgets
- Luxury purchases
- Unplanned furniture
- Multiple premium gifts
- Large impulse purchases
A discount does not automatically make an unaffordable purchase financially sensible.
3. Be Careful With Credit Cards During Diwali
Credit cards can be convenient during festive shopping, but they should not be treated as additional income.
A ₹50,000 credit-card purchase is still a ₹50,000 financial obligation.
If you cannot comfortably repay your spending, repeatedly adding purchases to the card can increase your outstanding balance.
RBI financial-awareness material also warns that using credit cards irresponsibly to fund expenses can contribute to increasing debt.
Before using your credit card, ask:
- Can I repay this purchase?
- When is the payment due?
- Do I already have an outstanding balance?
- Will this purchase affect my ability to pay existing EMIs?
- Am I buying it because I need it or because of a limited-time offer?
These simple questions can prevent unnecessary credit-card debt.
4. Do Not Confuse the Minimum Amount Due With Affordable Repayment
One common mistake is assuming that paying the minimum amount due means the credit-card debt is under control.
It does not necessarily mean the entire balance has been repaid.
RBI financial-awareness material explains that paying only the minimum amount can result in interest being charged on the remaining balance and can contribute to increasing debt.
Therefore, before making a large Diwali purchase on credit, understand how you will repay the balance.
A festive purchase should not become a multi-month financial burden simply because the initial payment appears small.
5. Protect Your Existing EMI Budget
If you already have personal loans, home loans, vehicle loans or other EMIs, your festive budget should come after your essential debt obligations.
For example, suppose your monthly income is ₹70,000.
Your regular commitments are:
- Household expenses: ₹30,000
- Loan EMIs: ₹25,000
- Utilities and other essentials: ₹8,000
That leaves ₹7,000 before considering savings and unexpected expenses.
Spending ₹30,000 on Diwali through a new loan or credit card may create a problem in the following months.
The festive budget should therefore reflect your actual disposable capacity, not simply your desired shopping list.
6. Avoid Taking a Personal Loan Just for Festival Shopping
Festive loan advertisements can make borrowing appear easy.
But a loan is not additional income.
It creates a repayment obligation.
RBI financial education material explicitly explains that borrowed money needs to be repaid and cautions consumers against borrowing for consumption expenses such as festival celebrations.
Before taking a loan for Diwali expenses, consider:
- Is the purchase genuinely necessary?
- Can it wait?
- Can it be funded through savings?
- What will the EMI be?
- How much interest will be paid?
- Will the new EMI affect existing financial commitments?
If the purchase is optional, postponing it may be financially wiser than borrowing for it.
7. Keep Your Emergency Savings Separate
One of the biggest financial mistakes during festive seasons is using every available rupee for shopping.
Unexpected expenses do not stop because it is Diwali.
Medical expenses, job changes, repairs, family emergencies or other financial requirements can occur at any time.
Therefore, avoid treating your entire savings balance as a festival budget.
A financially comfortable Diwali is one where you can celebrate without leaving yourself financially exposed afterward.
Diwali Spending on Credit Card: Is It Always Bad?
No.
Using a credit card is not automatically a bad financial decision.
The important question is whether the spending is manageable and whether you understand the repayment terms.
For example, if you have planned ₹20,000 of Diwali spending, have sufficient income to repay it and use the card responsibly, the purchase may be manageable.
The problem occurs when credit becomes a way to spend money that you do not actually have.
Warning signs include:
- Your credit-card balance keeps increasing.
- You are making only minimum payments.
- You use one credit card to manage another payment.
- You take a loan to repay credit-card spending.
- Your card is already near its limit.
- You are struggling to pay existing EMIs.
- You continue shopping despite knowing repayment will be difficult.
These can be signs that festive spending is adding to an existing debt problem.
What If You Already Have Credit Card Debt Before Diwali?
If you already have significant credit-card debt, adding another large balance may make repayment more difficult.
Instead of focusing only on Diwali offers, first understand your existing financial position.
Check:
- Total credit-card outstanding.
- Minimum amount due.
- Total amount required for repayment.
- Interest and applicable charges.
- Other loan EMIs.
- Monthly household expenses.
- Available savings.
- Upcoming financial commitments.
Then determine whether additional festive spending is realistically affordable.
If your existing debt is already difficult to manage, consider speaking with the relevant lender about the options available to you rather than simply adding more borrowing.
What If You Cannot Pay Your Loan EMI During the Festive Season?
This is an important distinction.
If you are temporarily facing a cash-flow problem, do not automatically assume that taking another loan is the answer.
First understand why the EMI has become difficult to manage.
Possible reasons include:
- Temporary income disruption
- Unexpected household expenses
- Job loss
- Business cash-flow problems
- Multiple loan obligations
- Growing credit-card balances
- Previous borrowing
- Higher overall monthly commitments
Depending on your circumstances, options may include discussing repayment difficulties with the lender, examining whether restructuring is available, reviewing your overall debt position, or seeking professional debt-resolution guidance.
Do not deliberately stop paying an EMI simply to force a settlement. Understand the consequences and communicate with the lender wherever possible.
Can Diwali Spending Lead to a Debt Trap?
It can, particularly when festive expenses are repeatedly funded through new borrowing.
A typical cycle can look like this:
Festive shopping → Credit-card balance → Difficulty repaying → New borrowing → Higher monthly obligations → Further financial stress
If this cycle continues, a person may find that an expense originally intended for a short celebration has become a long-term repayment problem.
The key is to identify the problem early.
A Simple Diwali Financial Planning Checklist
Before the festive season begins, ask yourself:
Income
- What is my monthly take-home income?
- Is my income stable?
Existing debt
- How much do I pay in EMIs every month?
- Do I already have credit-card outstanding?
- Are any payments overdue?
Savings
- How much money can I safely use?
- Am I protecting emergency savings?
Diwali expenses
- What do I actually need?
- What can I postpone?
- What is my maximum festive budget?
Borrowing
- Am I considering a new loan?
- Can I afford the EMI?
- Am I using credit because I genuinely need the purchase or because I do not have enough cash?
After Diwali
- How will I pay for the purchases?
- Will the spending affect next month's EMI payments?
- Will I still have enough money for essential expenses?
If the answers reveal that the spending is unaffordable, reducing the budget is usually safer than increasing borrowing.
What Should You Do If Your Debt Is Already Difficult to Manage?
Diwali spending may sometimes reveal a larger financial problem.
For example, you may realise that:
- Your EMIs consume a large portion of your income.
- Credit-card balances have been increasing.
- You have multiple personal loans.
- You are using new credit to repay older obligations.
- You are struggling to meet monthly payments.
- Recovery calls have become a source of stress.
- Your outstanding debt is significantly higher than your repayment capacity.
In such circumstances, the solution is not necessarily to find another loan.
Instead, take a complete view of your financial position.
Depending on your circumstances, you may explore options such as:
- Continuing regular repayment
- Discussing available repayment options with the lender
- Restructuring, where applicable
- Debt consolidation, where appropriate
- Professional debt-resolution guidance
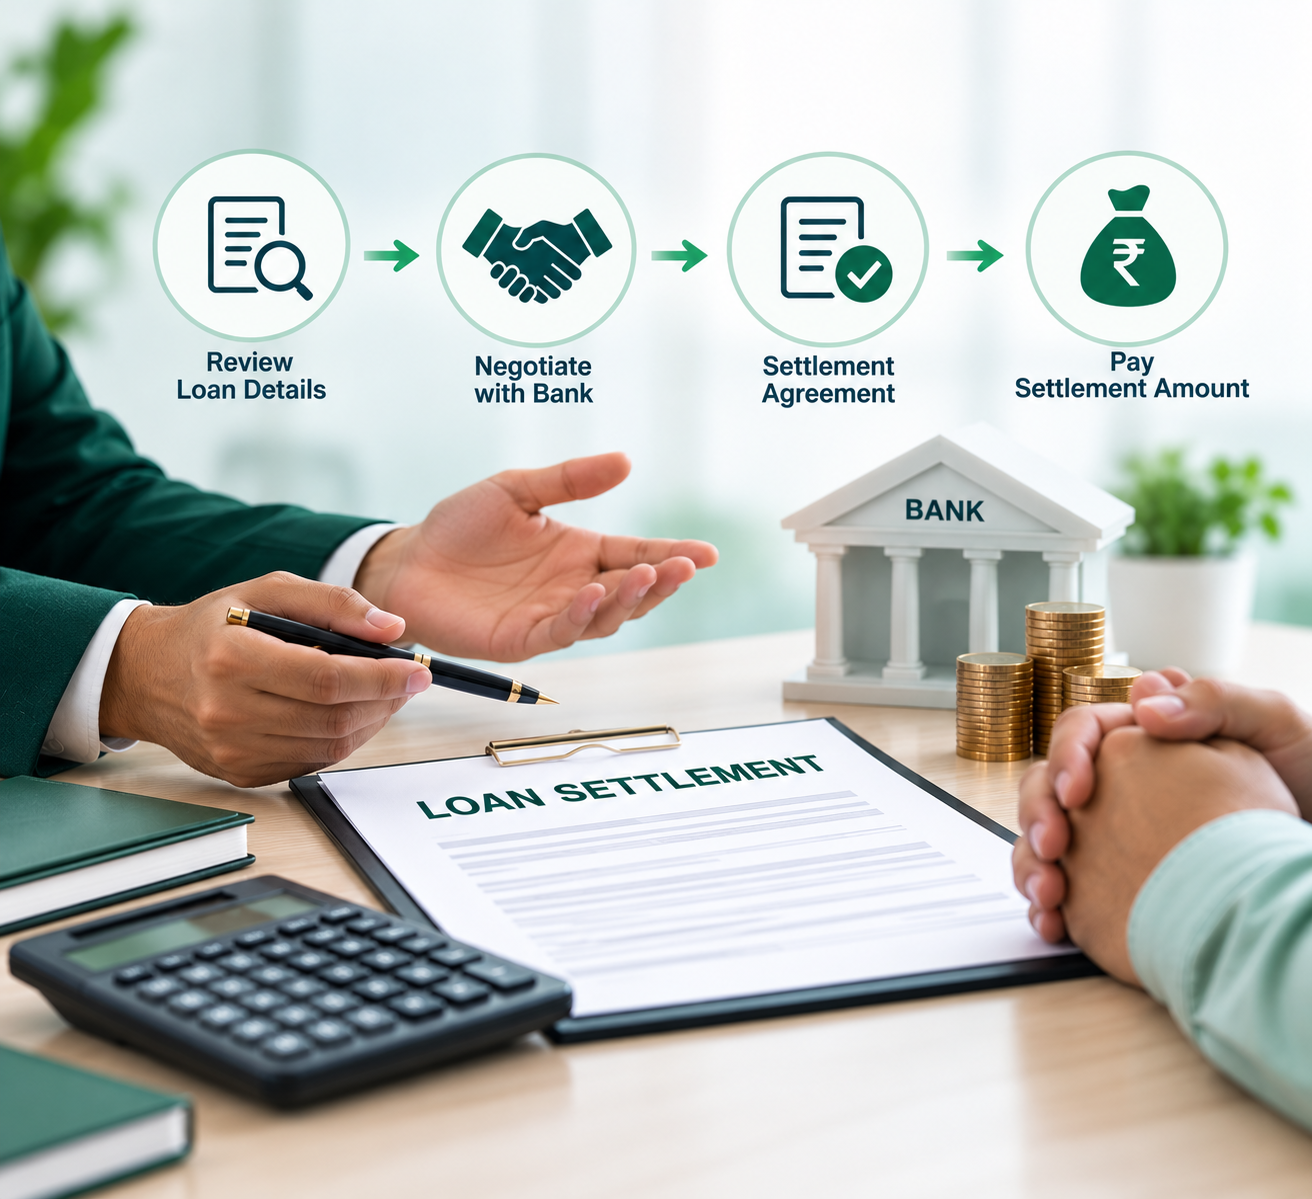
- Loan settlement, where genuine financial hardship exists and the lender agrees
Loan settlement is not the same as normal loan closure, and it should not be treated as an automatic solution for every borrower.
Does Loan Settlement Affect Your Credit Profile?
Potentially, yes.
If a lender agrees to accept an amount lower than the total outstanding and reports the account as “settled”, that status can be viewed negatively by future lenders.
CIBIL explains that a “settled” account indicates that the borrower made a partial payment with the lender's consent against the total outstanding, and that settled accounts are not viewed as favourably as closed accounts by lenders.
Therefore, borrowers should understand the possible credit consequences before considering settlement.
The objective should not simply be to reduce an immediate financial burden. It should also be to make an informed decision about longer-term financial health.
Diwali Financial Planning: A Better Way to Think About Festive Spending
Instead of asking:
“How much can I spend this Diwali?”
ask:
“How much can I spend without affecting my financial responsibilities?”
That small change in thinking can make a significant difference.
A sustainable Diwali budget should protect:
Essential expenses → Existing EMIs → Emergency savings → Future commitments → Festive spending
This does not mean avoiding celebrations.
It means making celebrations fit your financial reality.
10 Smart Rules for a Debt-Free Diwali
Here is a simple checklist you can save or share:
- Set your Diwali budget before shopping.
- Do not treat credit as income.
- Keep existing EMI payments a priority.
- Avoid unnecessary personal loans for festival purchases.
- Do not rely only on minimum credit-card payments.
- Compare prices before buying expensive items.
- Separate needs from festive impulse purchases.
- Protect your emergency savings.
- Track spending throughout the festive season.
- If existing debt is already unmanageable, address the debt problem before adding new borrowing.
Final Thoughts: Celebrate Diwali, Not Financial Stress
Diwali is meant to bring light, happiness and togetherness. It does not need to come with months of financial stress.
The best festive budget is not necessarily the biggest one. It is the one that allows you to celebrate while remaining financially comfortable afterward.
Before making that next Diwali purchase, pause and ask:
Can I afford this without c